


Market Overview - Page 4
September 25, 2026
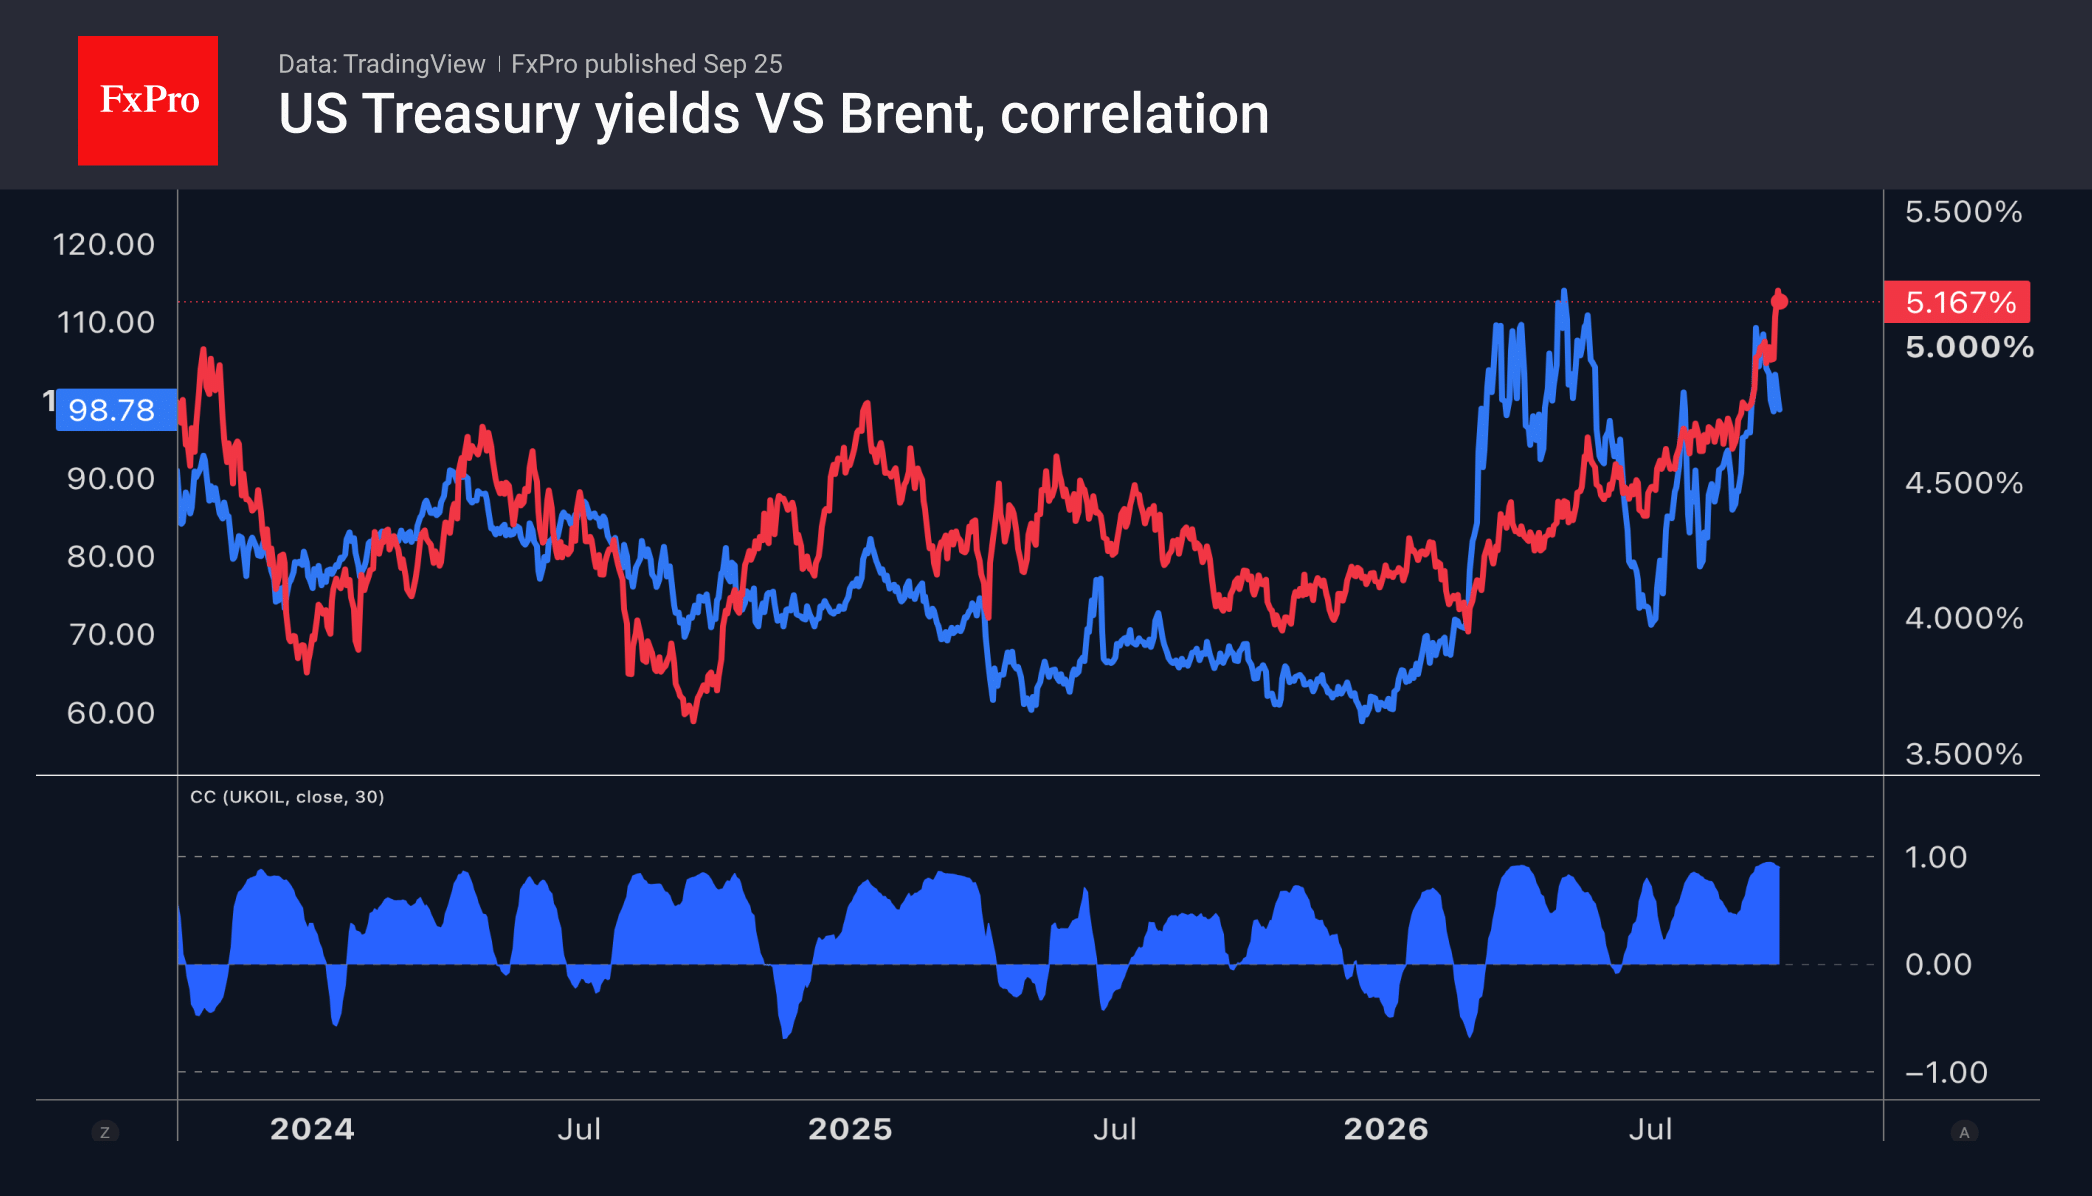
USDJPY is retreating amid falling yields and a weaker dollar, but the US dollar remains strong on expectations of further Fed tightening.
September 24, 2026
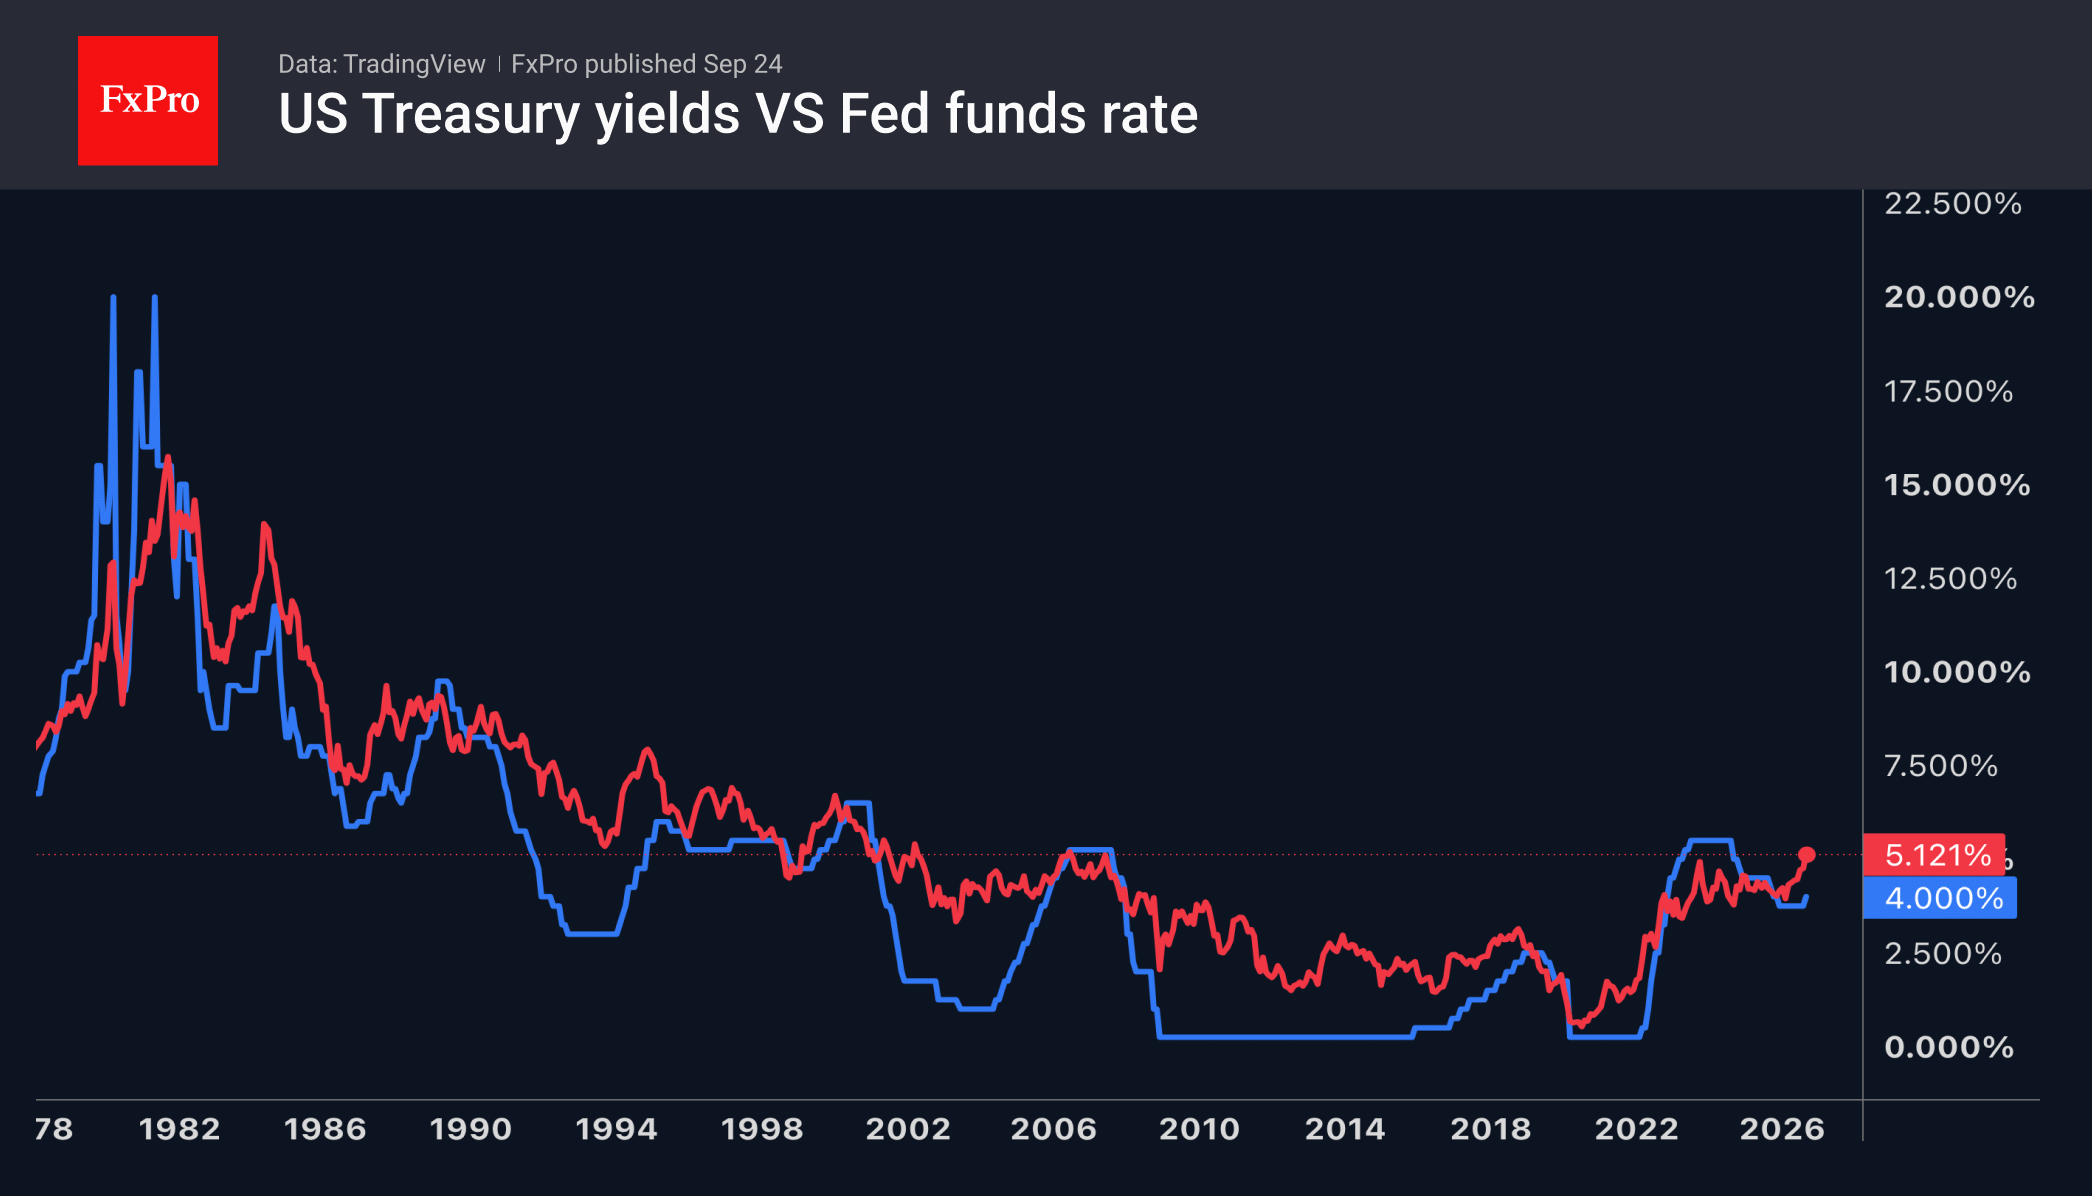
The dollar is strengthening on expectations of a Fed rate hike and rising yields, whilst the yen’s weakness maintains the risk of intervention at 160 on USDJPY.
September 23, 2026
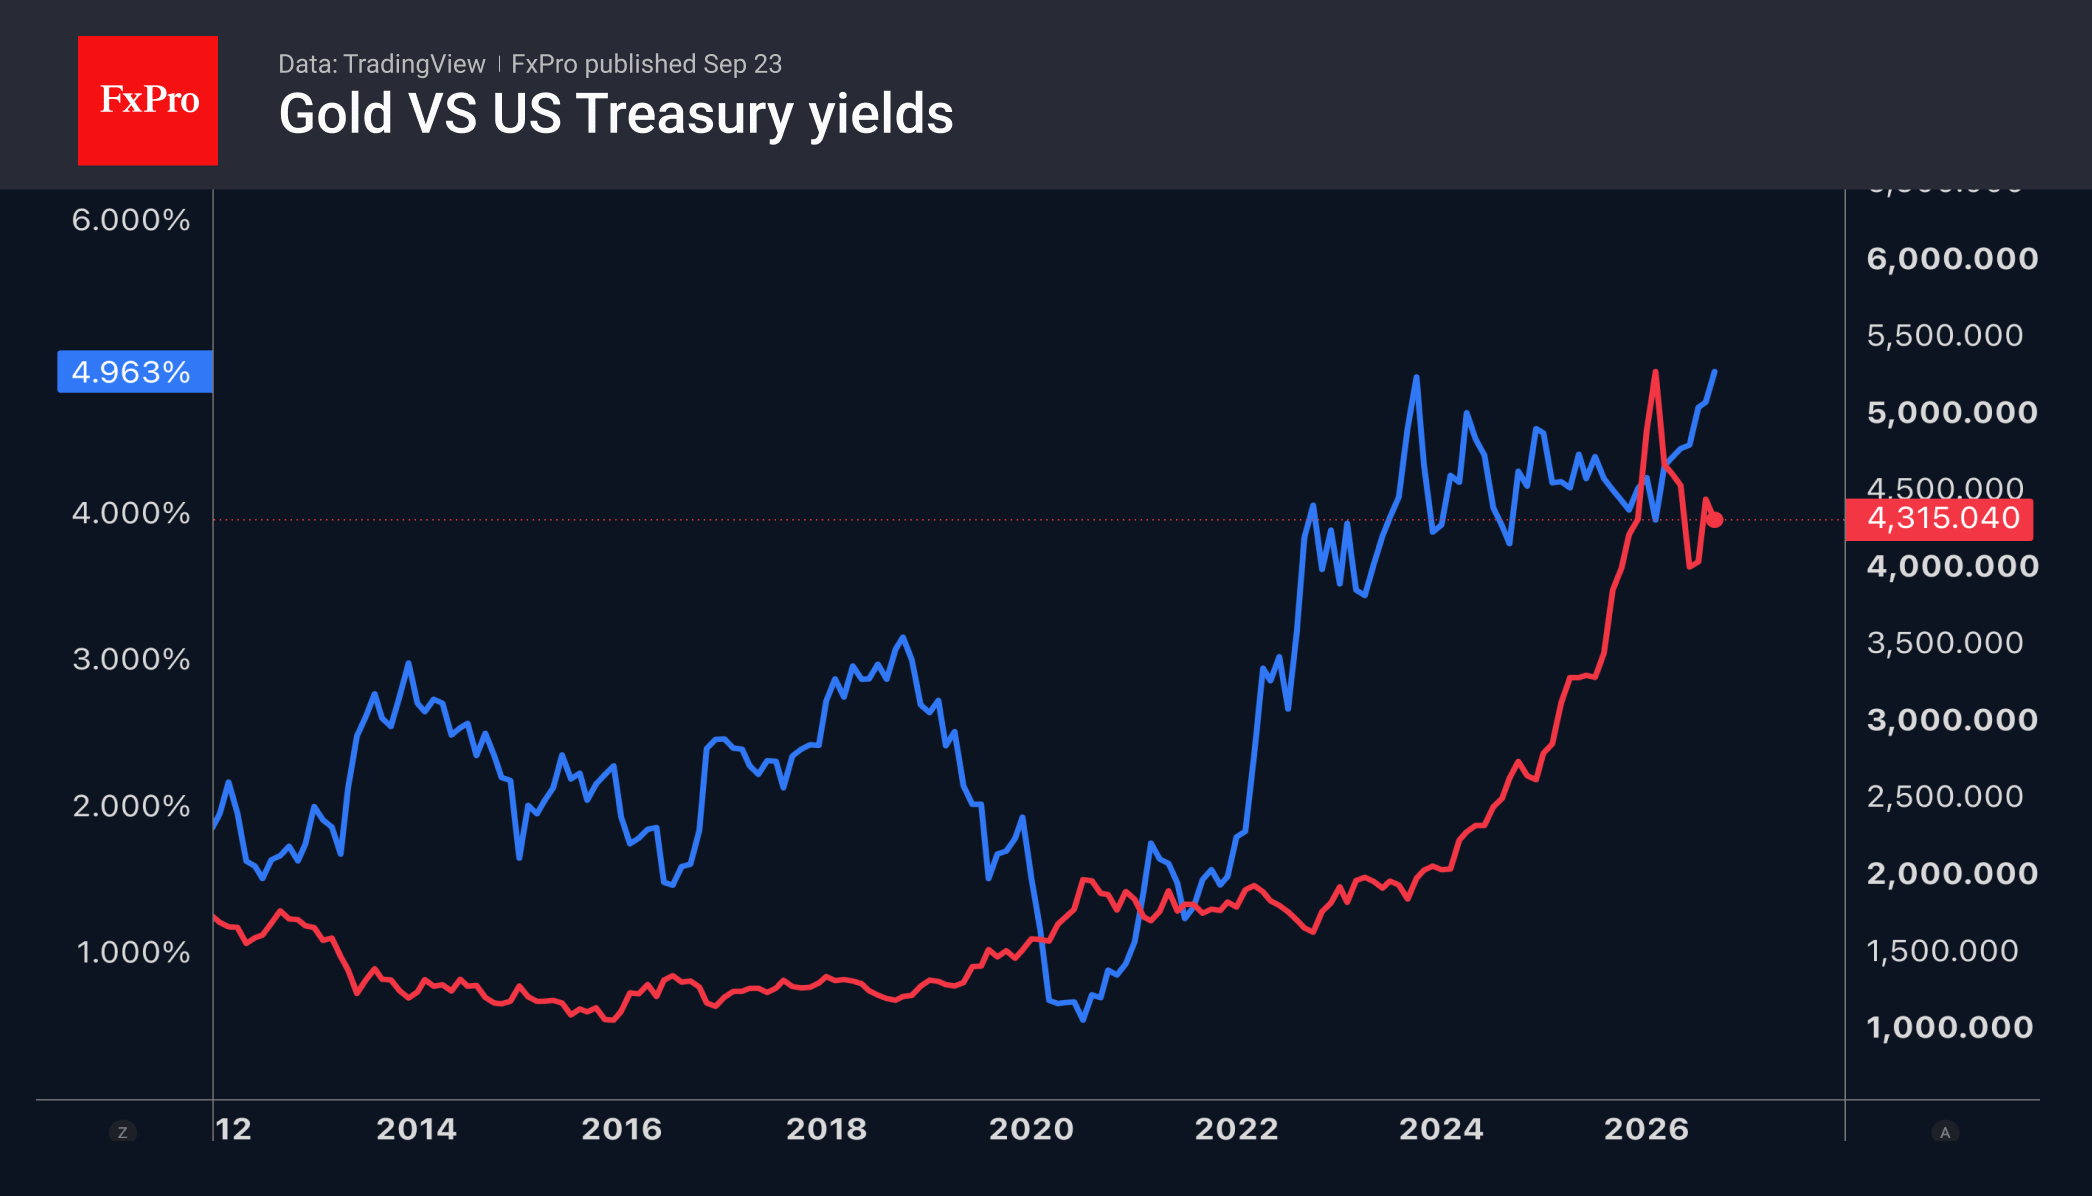
Gold is consolidating at $4,250–4,400 as dollar pressure is offset by Asian demand, ETF buying, and central bank buying.
September 23, 2026
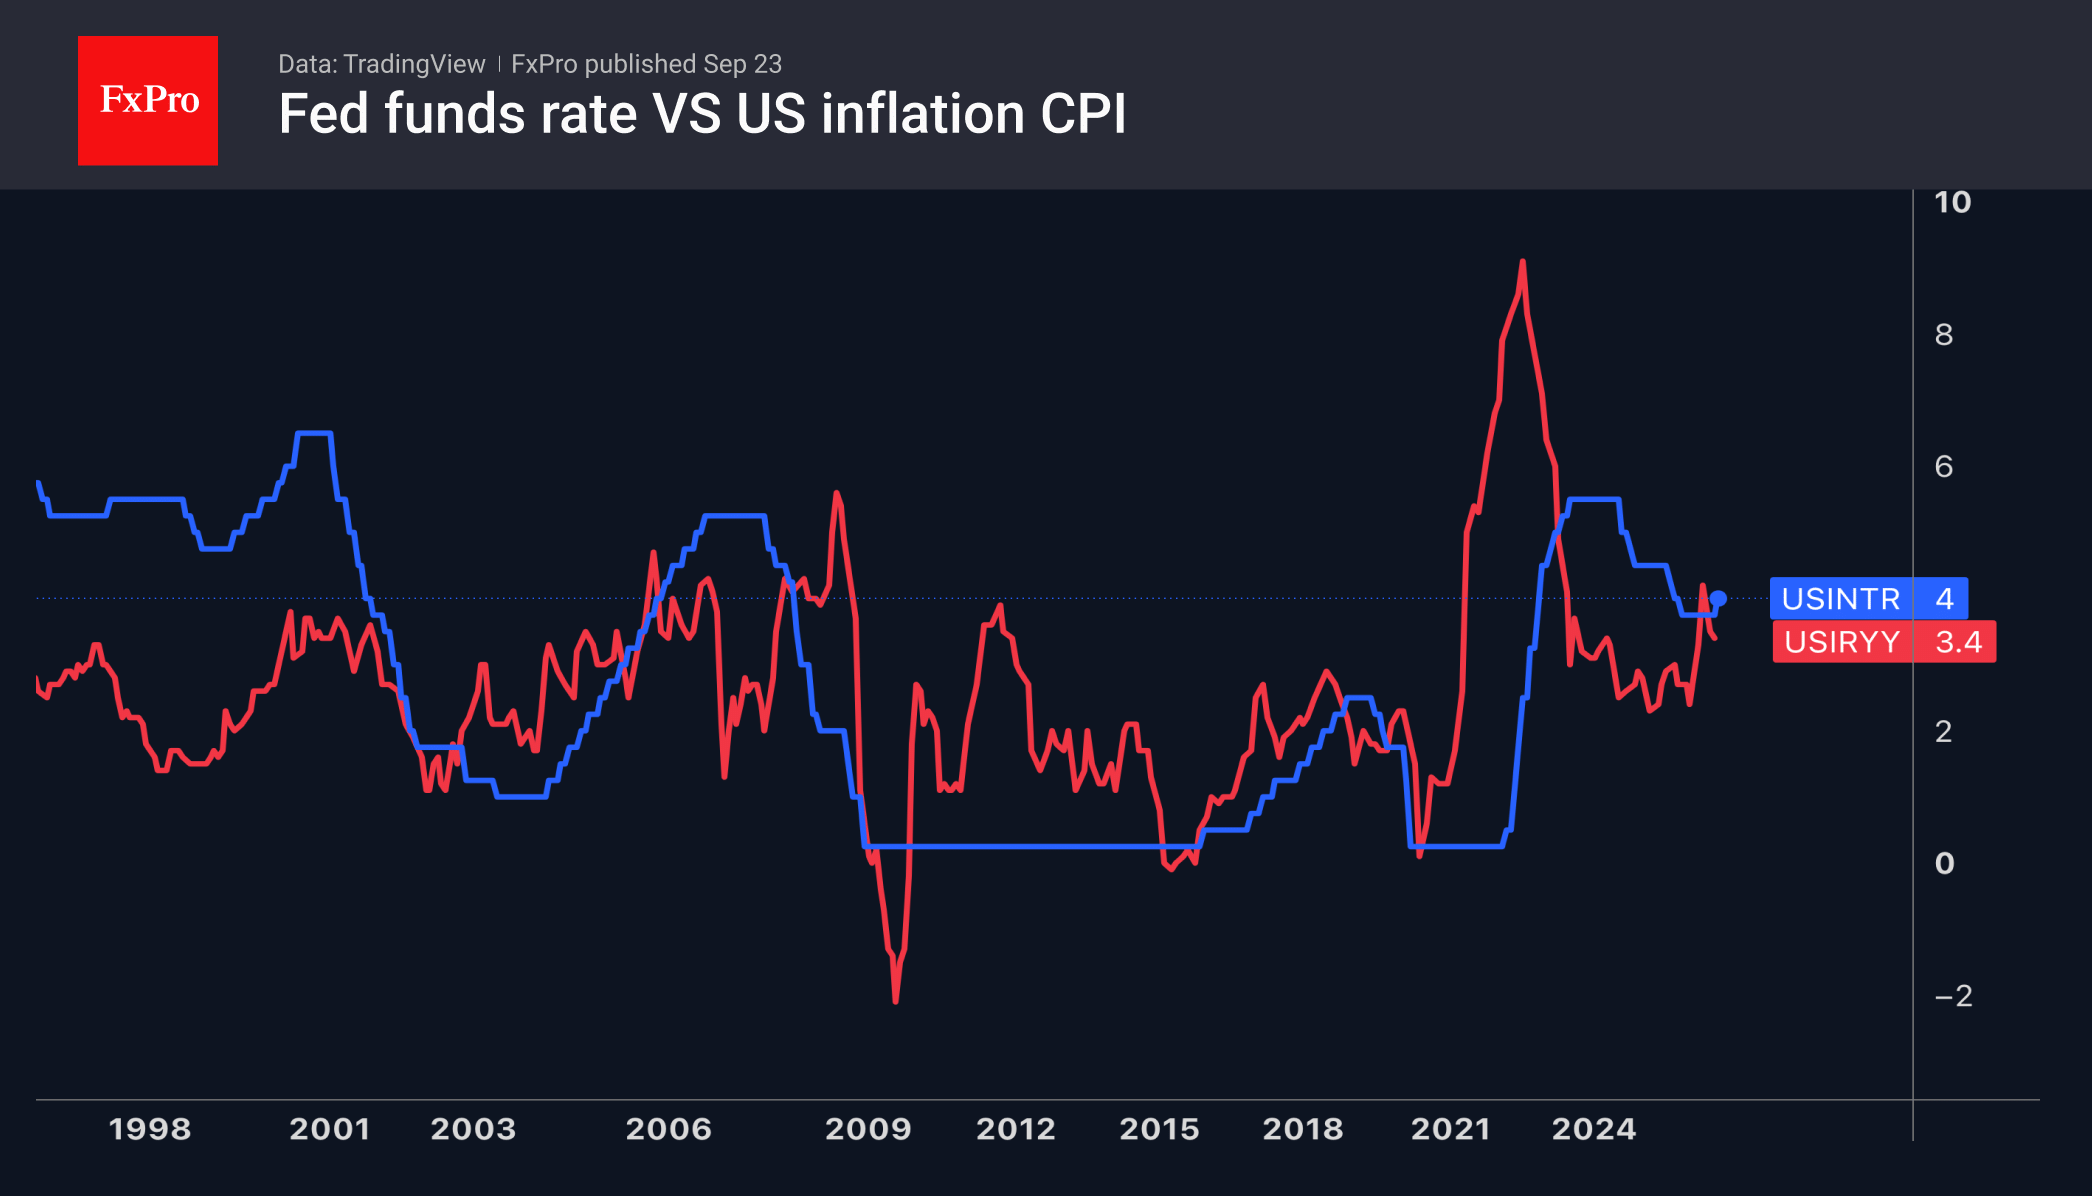
The dollar has risen for 7 sessions (+2%). Political risks weigh on the euro and pound: France’s debt may top 120% of GDP, and the UK budget spooks markets. The yen slips on the BoJ’s lack of urgency.
September 22, 2026
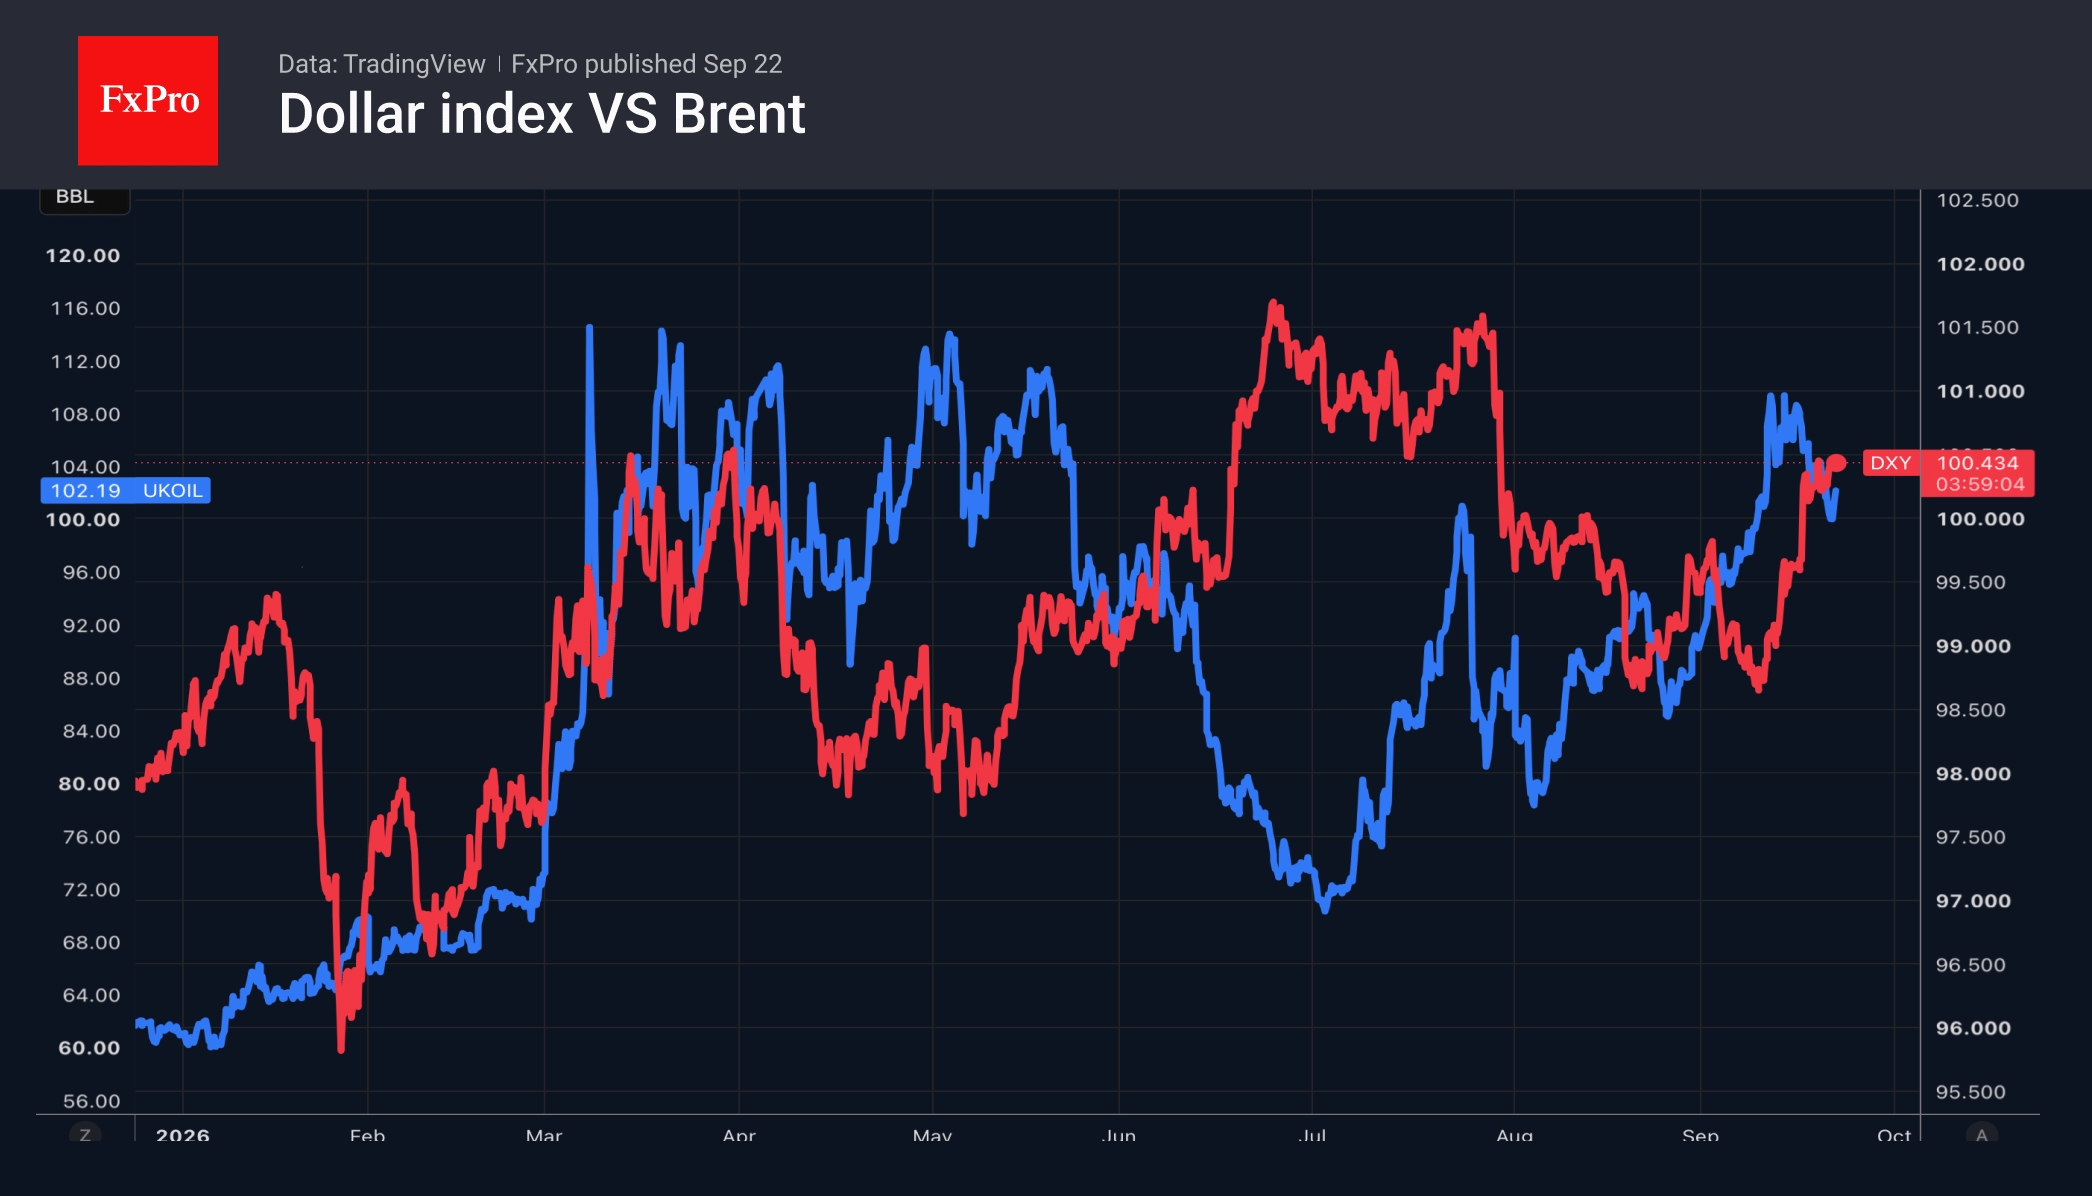
The dollar is rising in tandem with oil prices: inflation risks and the prospect of Fed tightening are supporting the USD, whilst political risks in Germany are weighing on the euro.
September 21, 2026
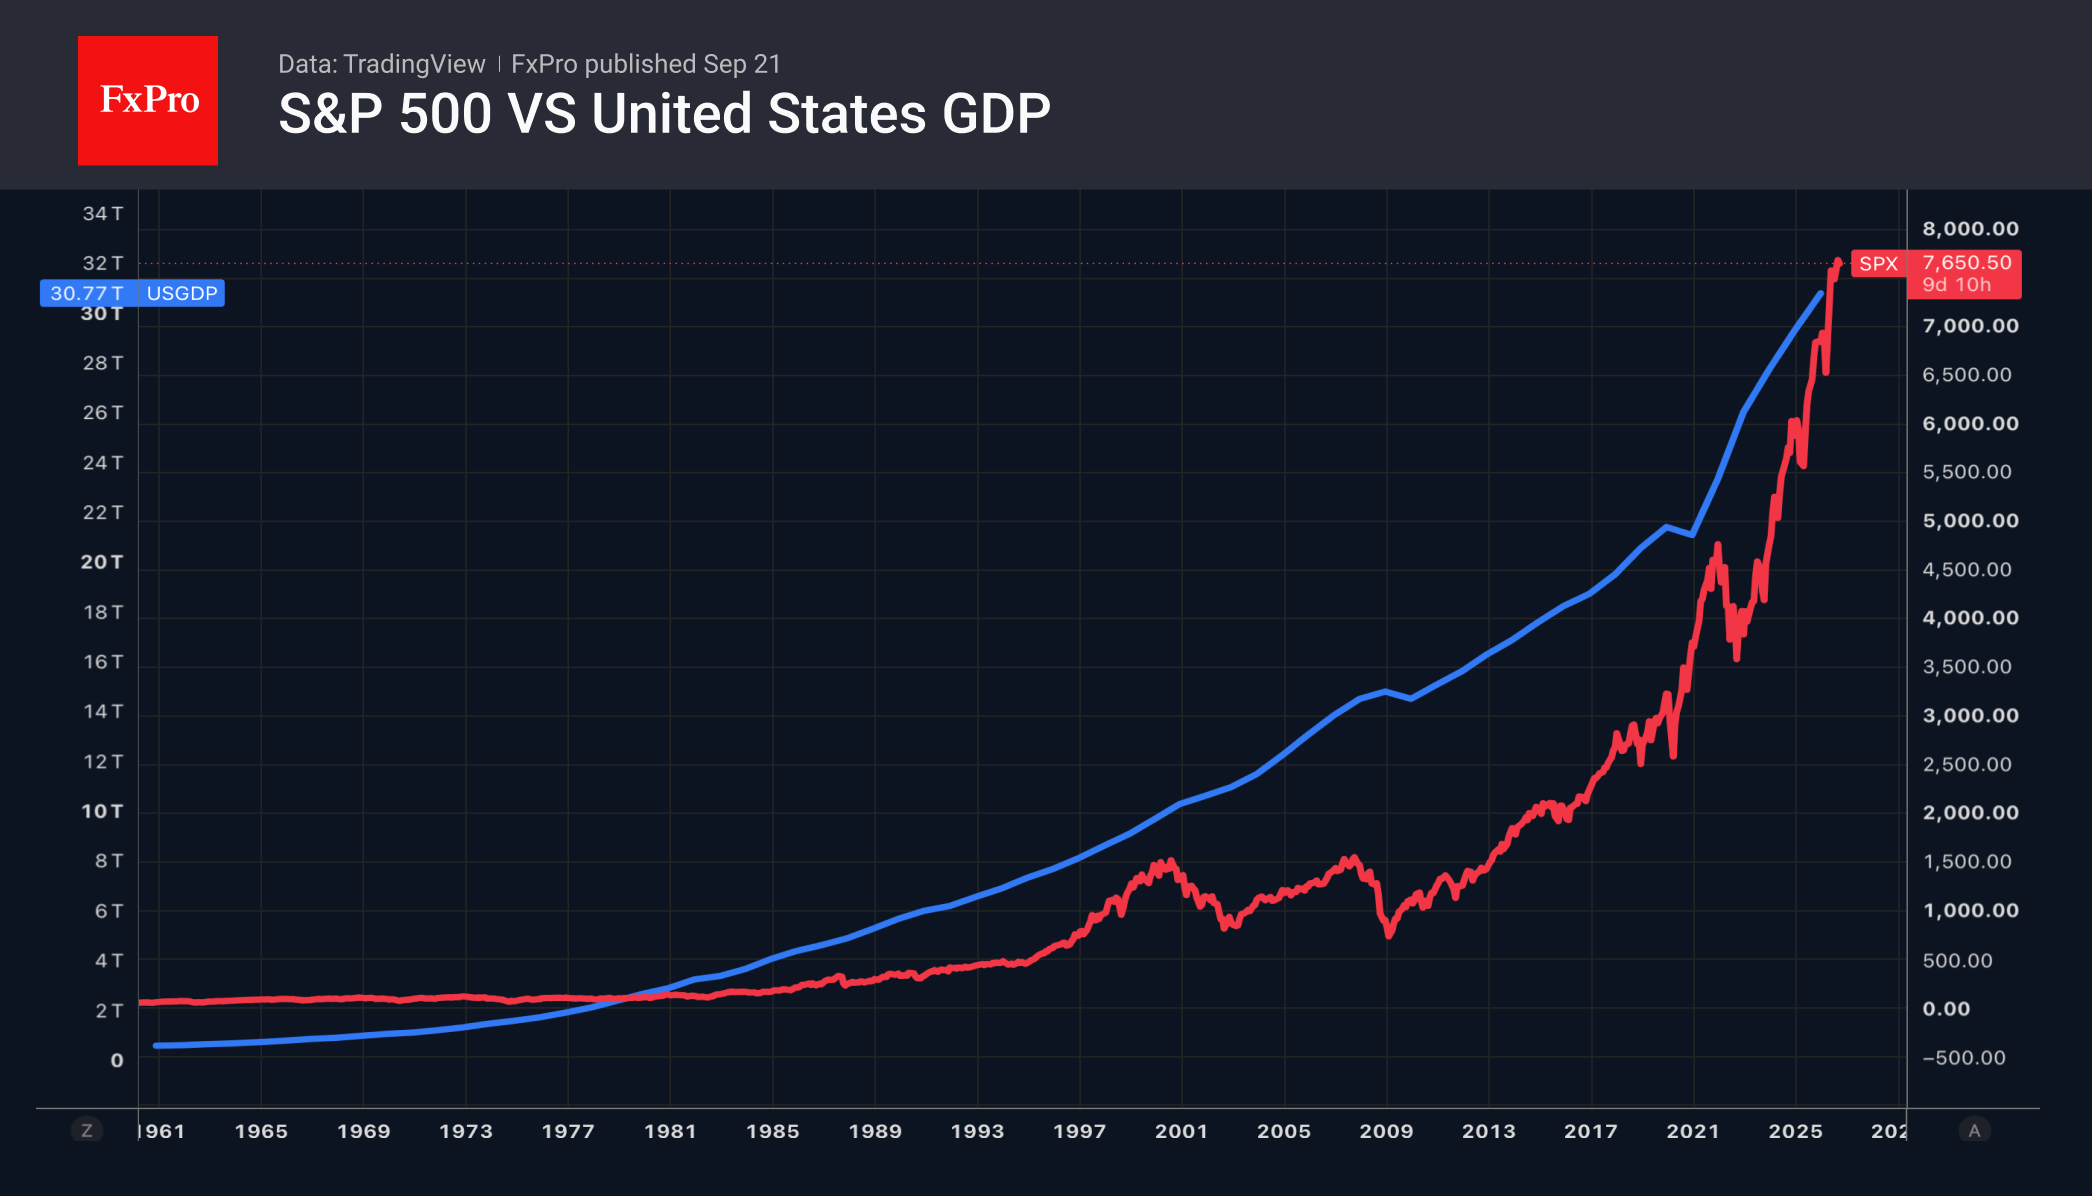
The S&P 500 stays resilient as a strong economy and solid profits offset Fed tightening, though oil-driven stagflation risks could trigger a correction.
September 21, 2026
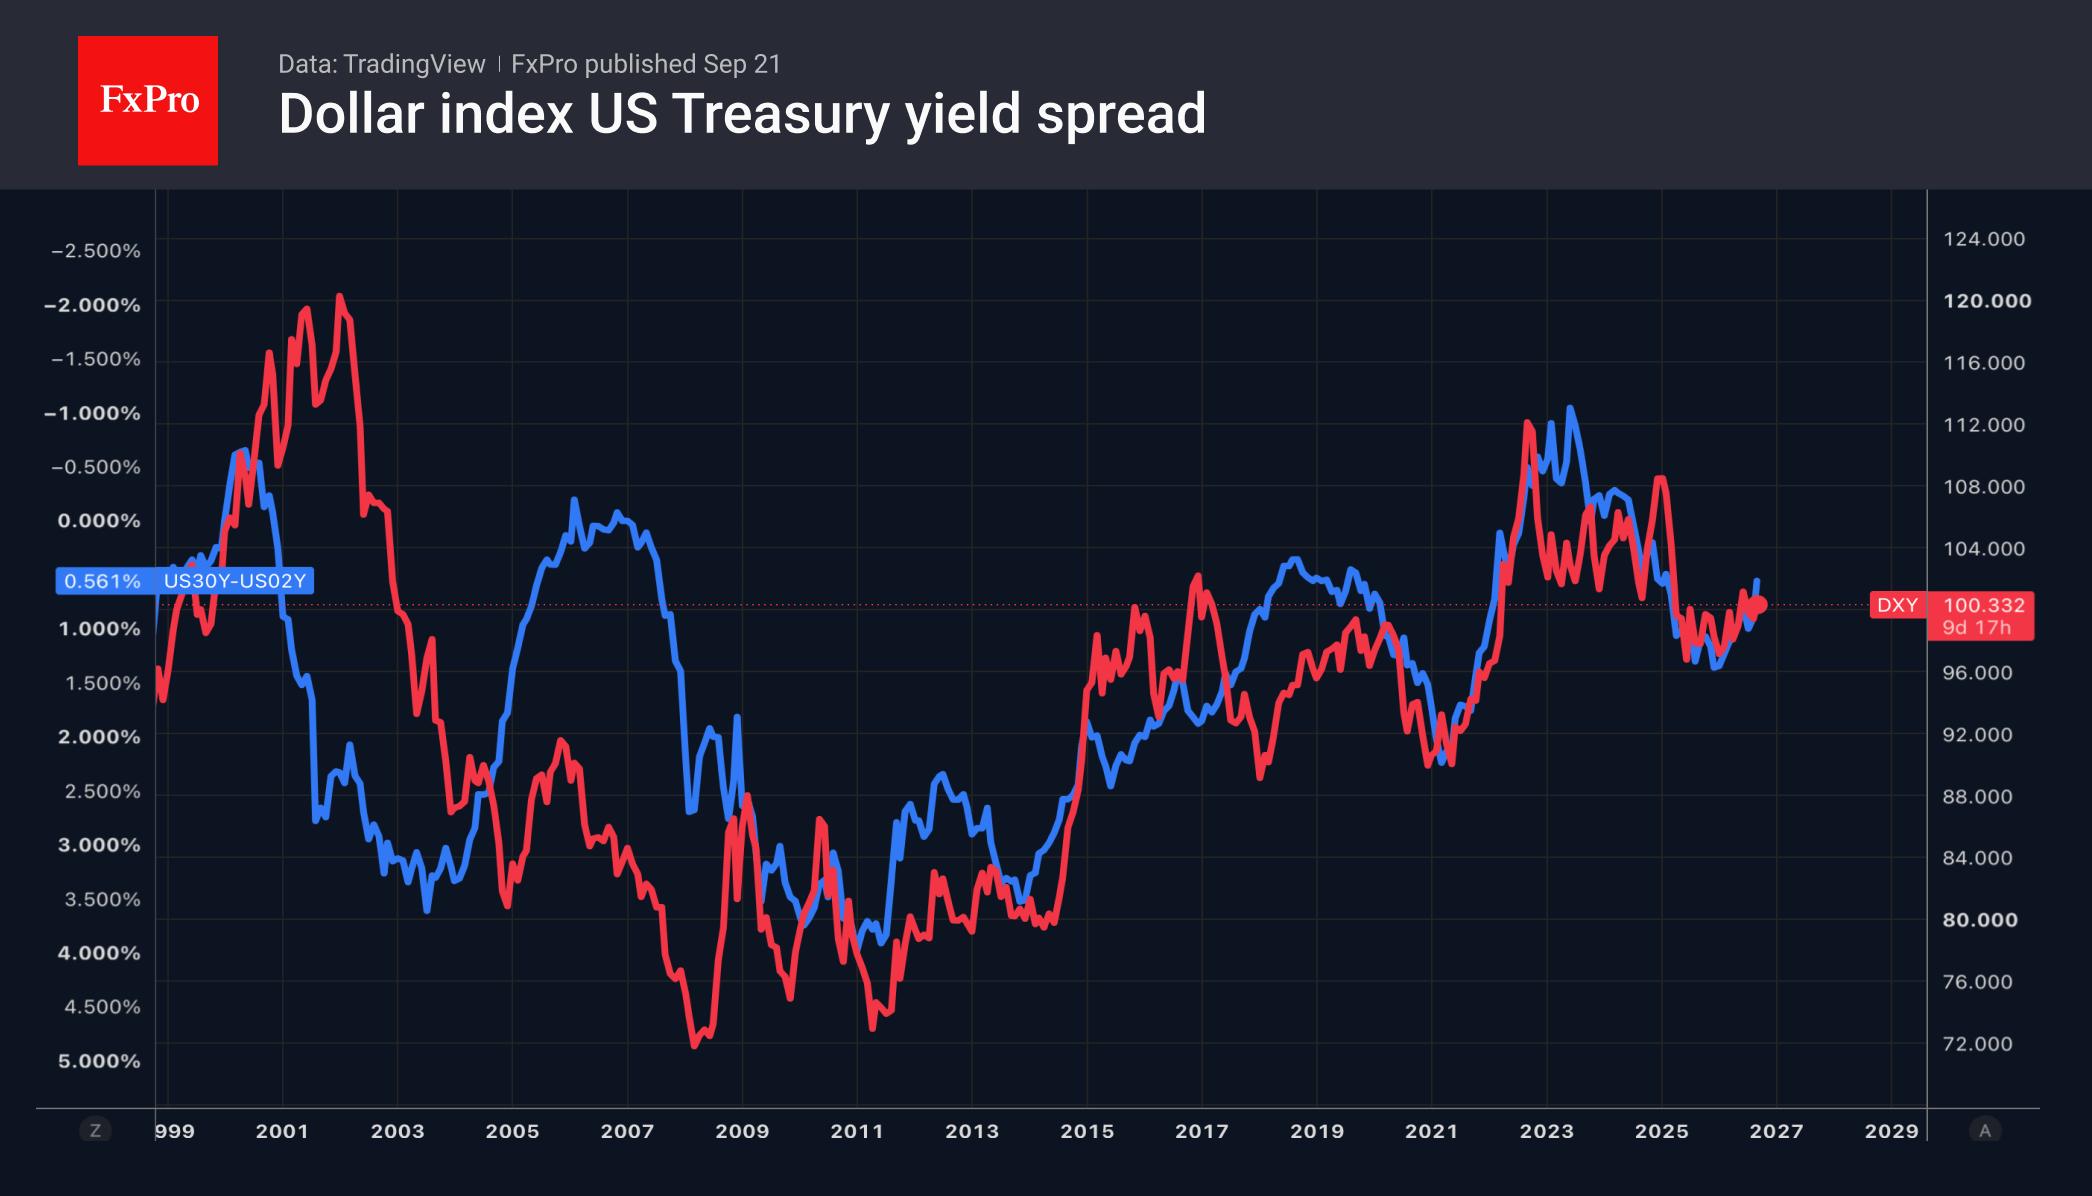
The euro is finding support from reassessments of interest rates by the Fed and the ECB, while the yen's return as a funding currency is helping EURUSD hold its ground.
September 18, 2026
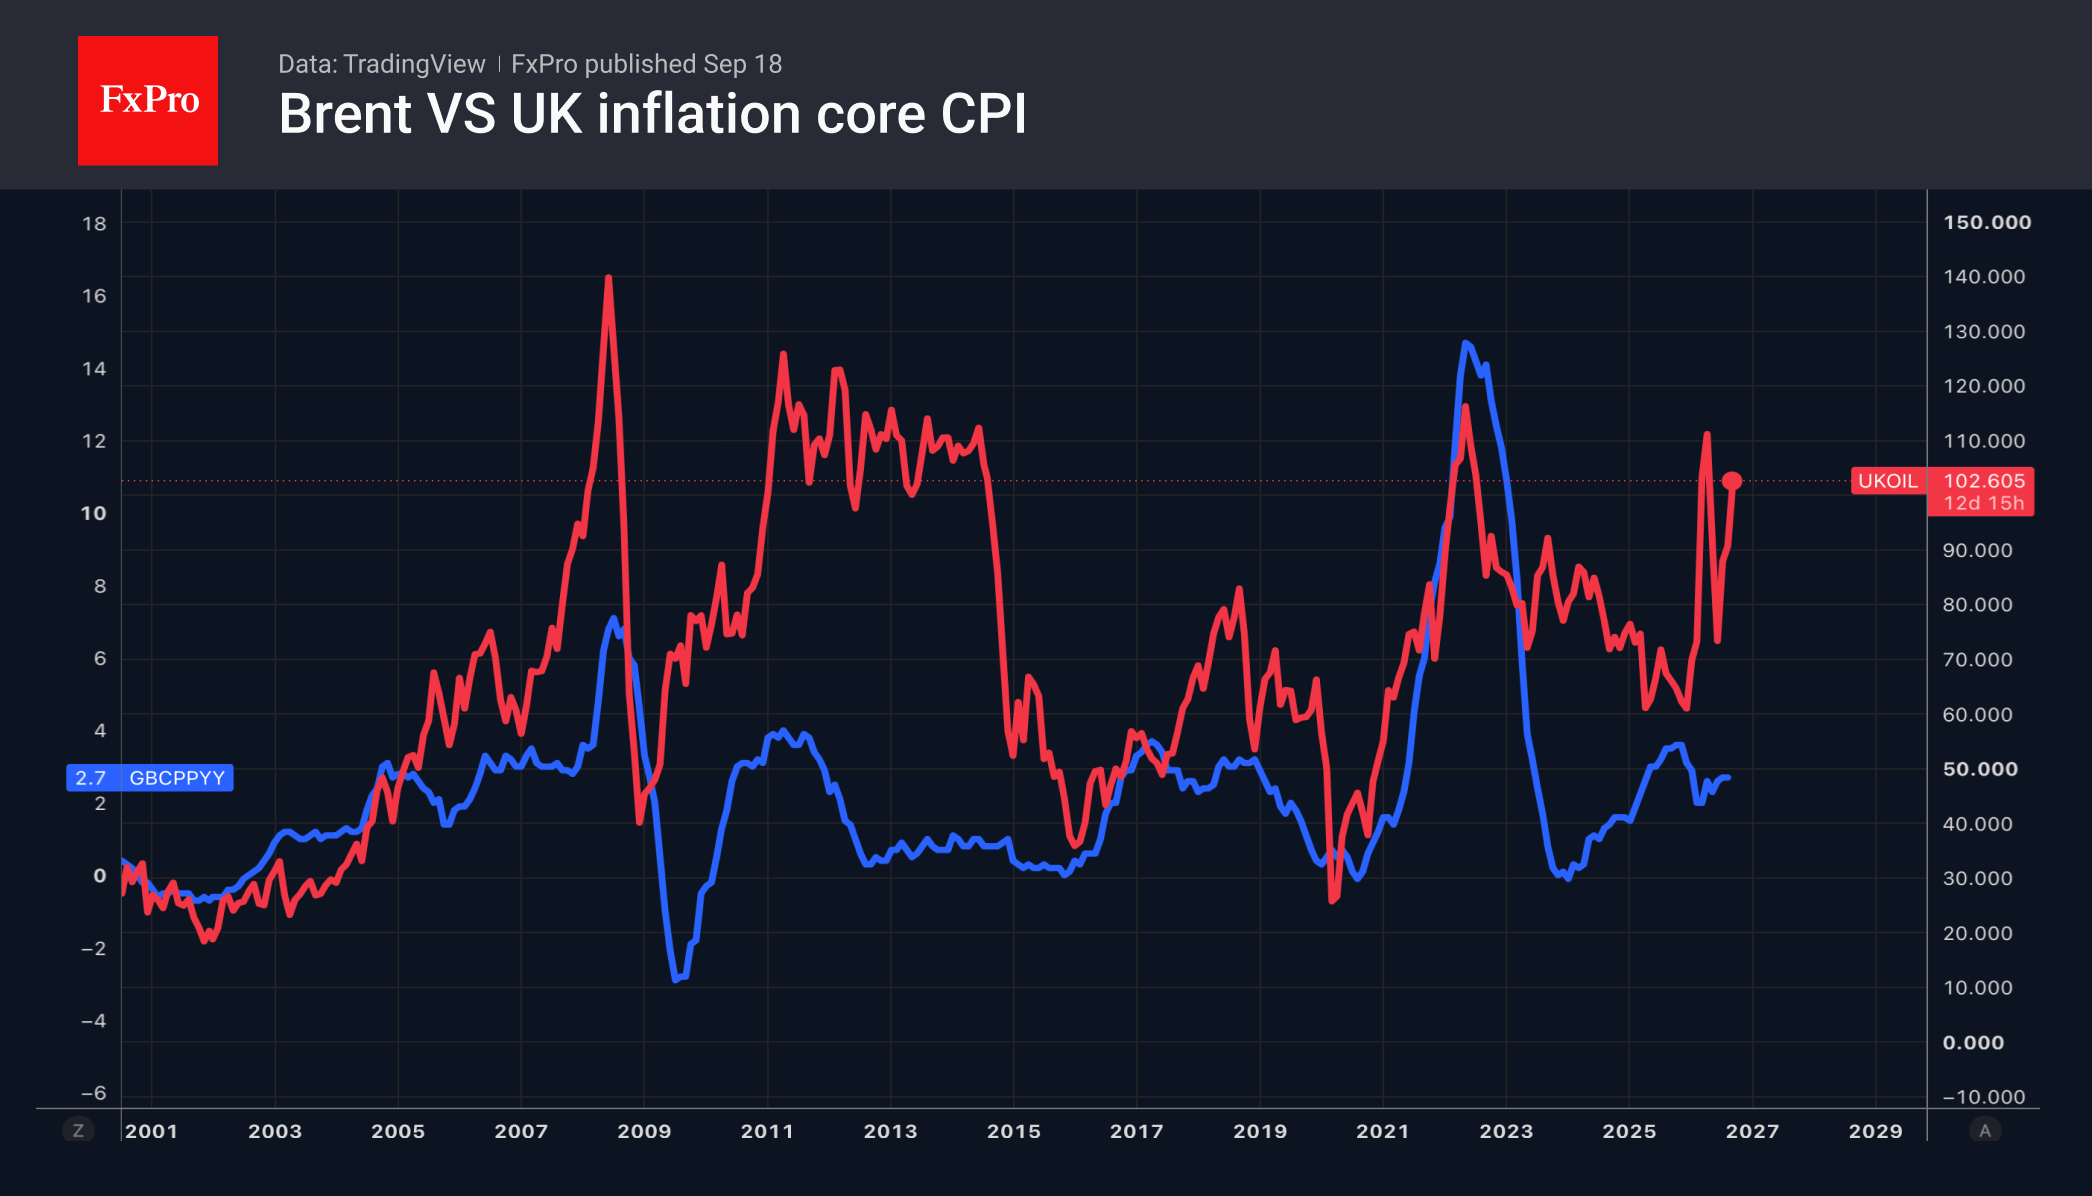
The dollar is gaining on the hawkish Fed, slower BoE, and BoJ; USDJPY is nearing the zone where intervention risks rise.
September 17, 2026
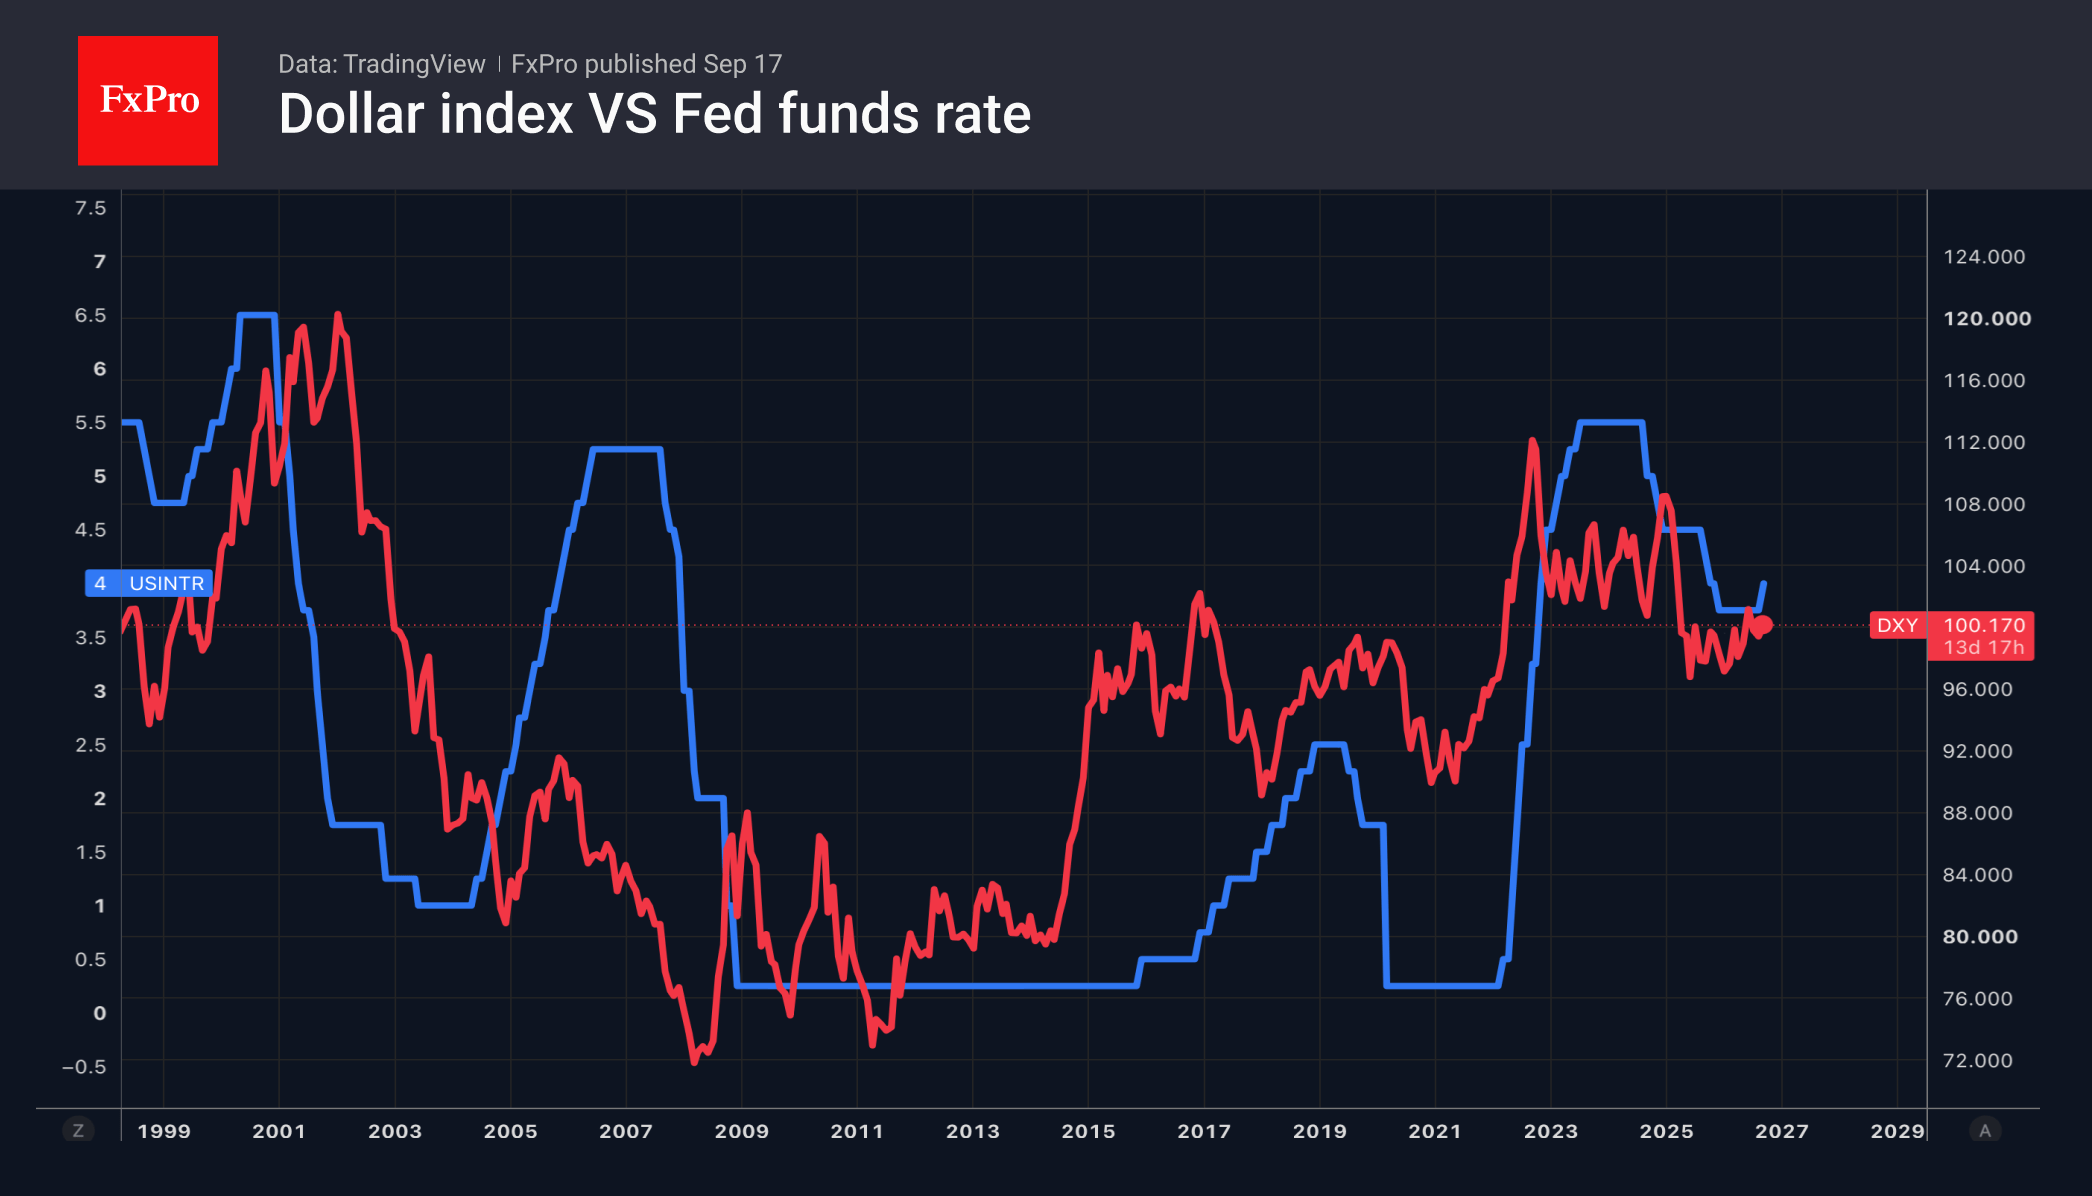
The Fed has raised rates and strengthened the dollar; the Bank of England may respond with a hawkish signal, supporting the pound.
September 16, 2026
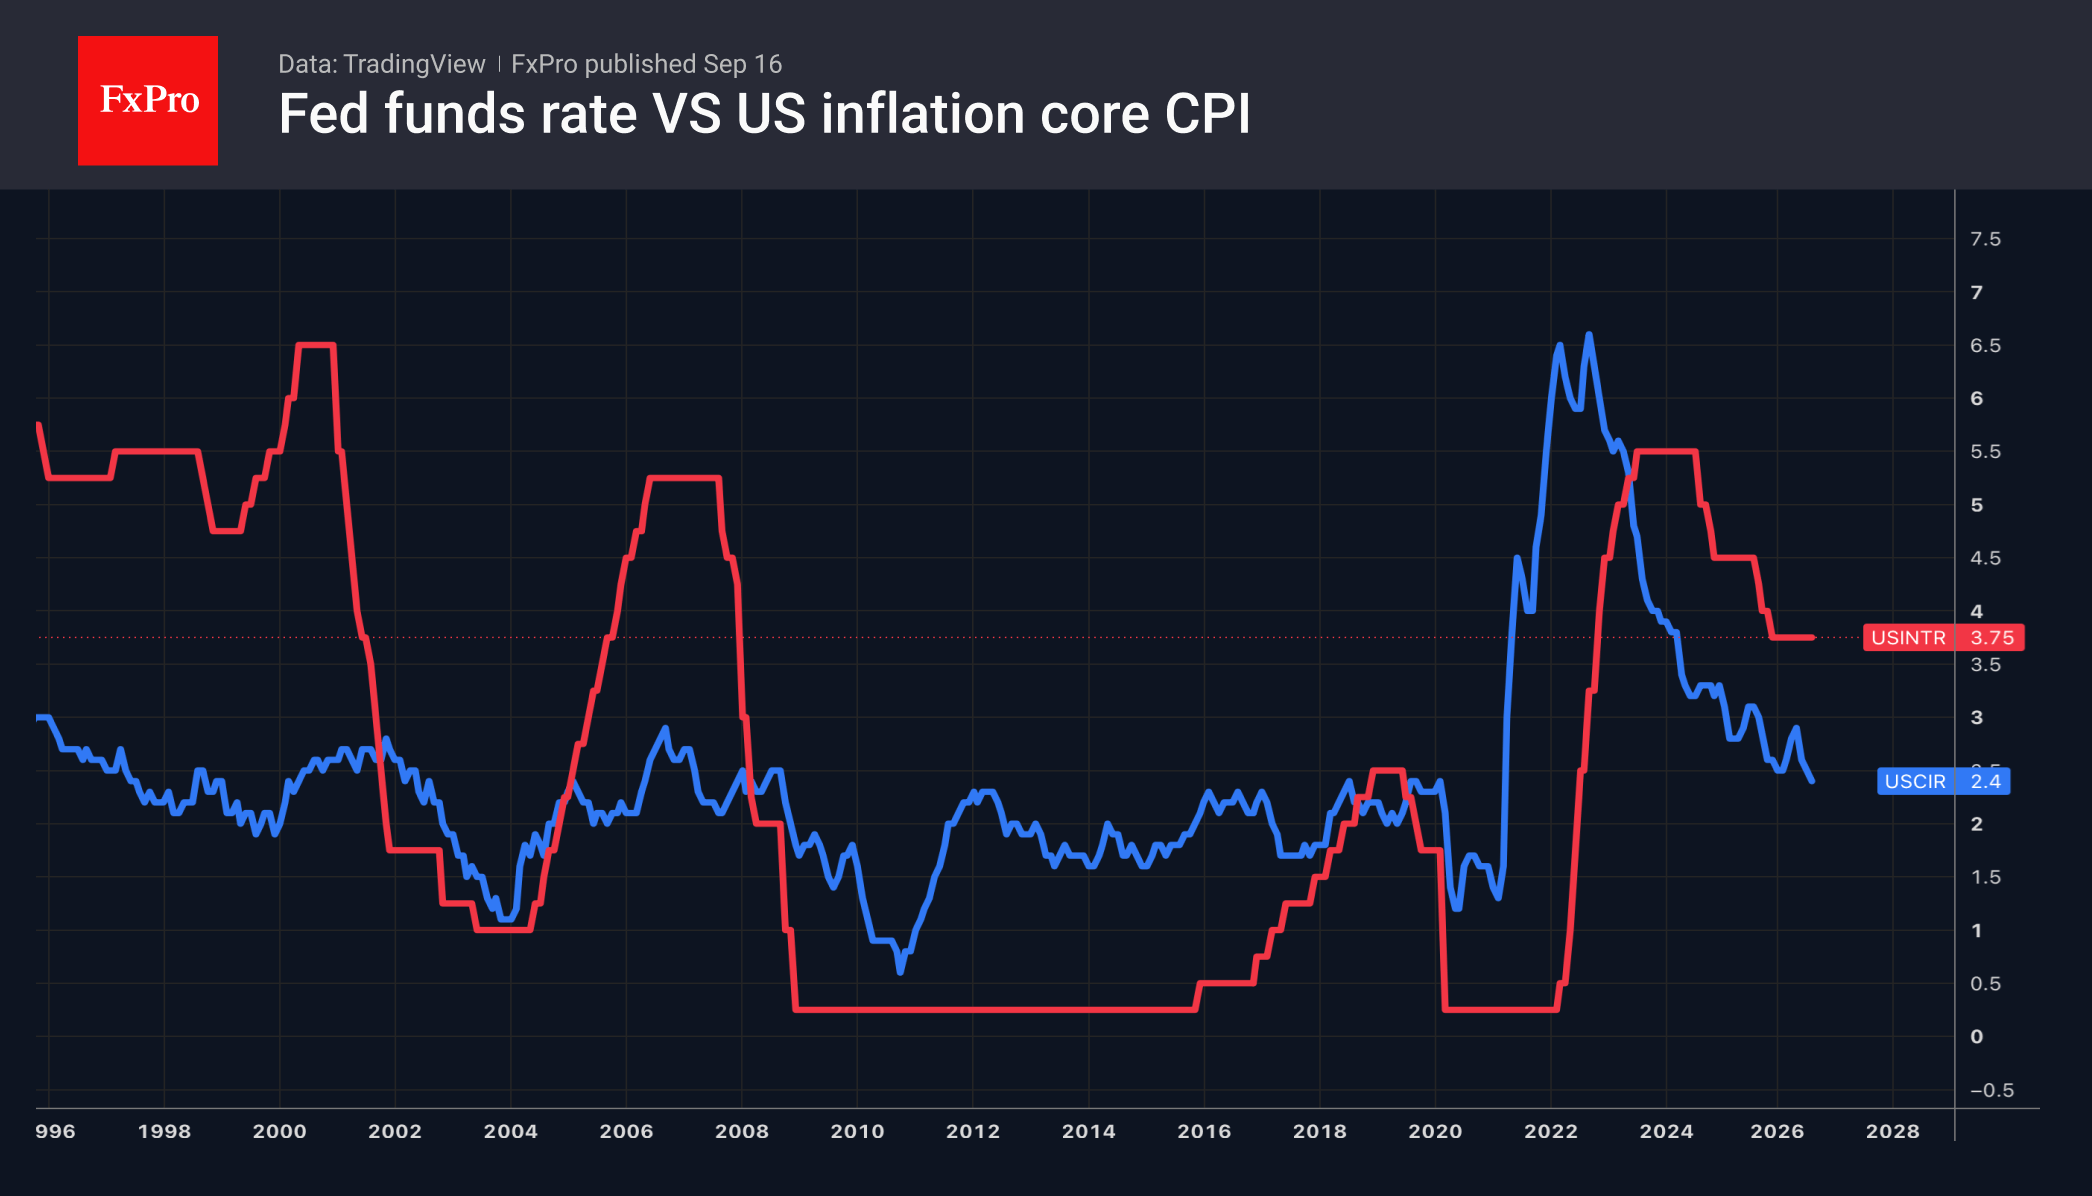
The Fed may begin a hiking cycle; the dollar will only gain ground if the signals are more hawkish; otherwise, a correction is likely.
September 15, 2026
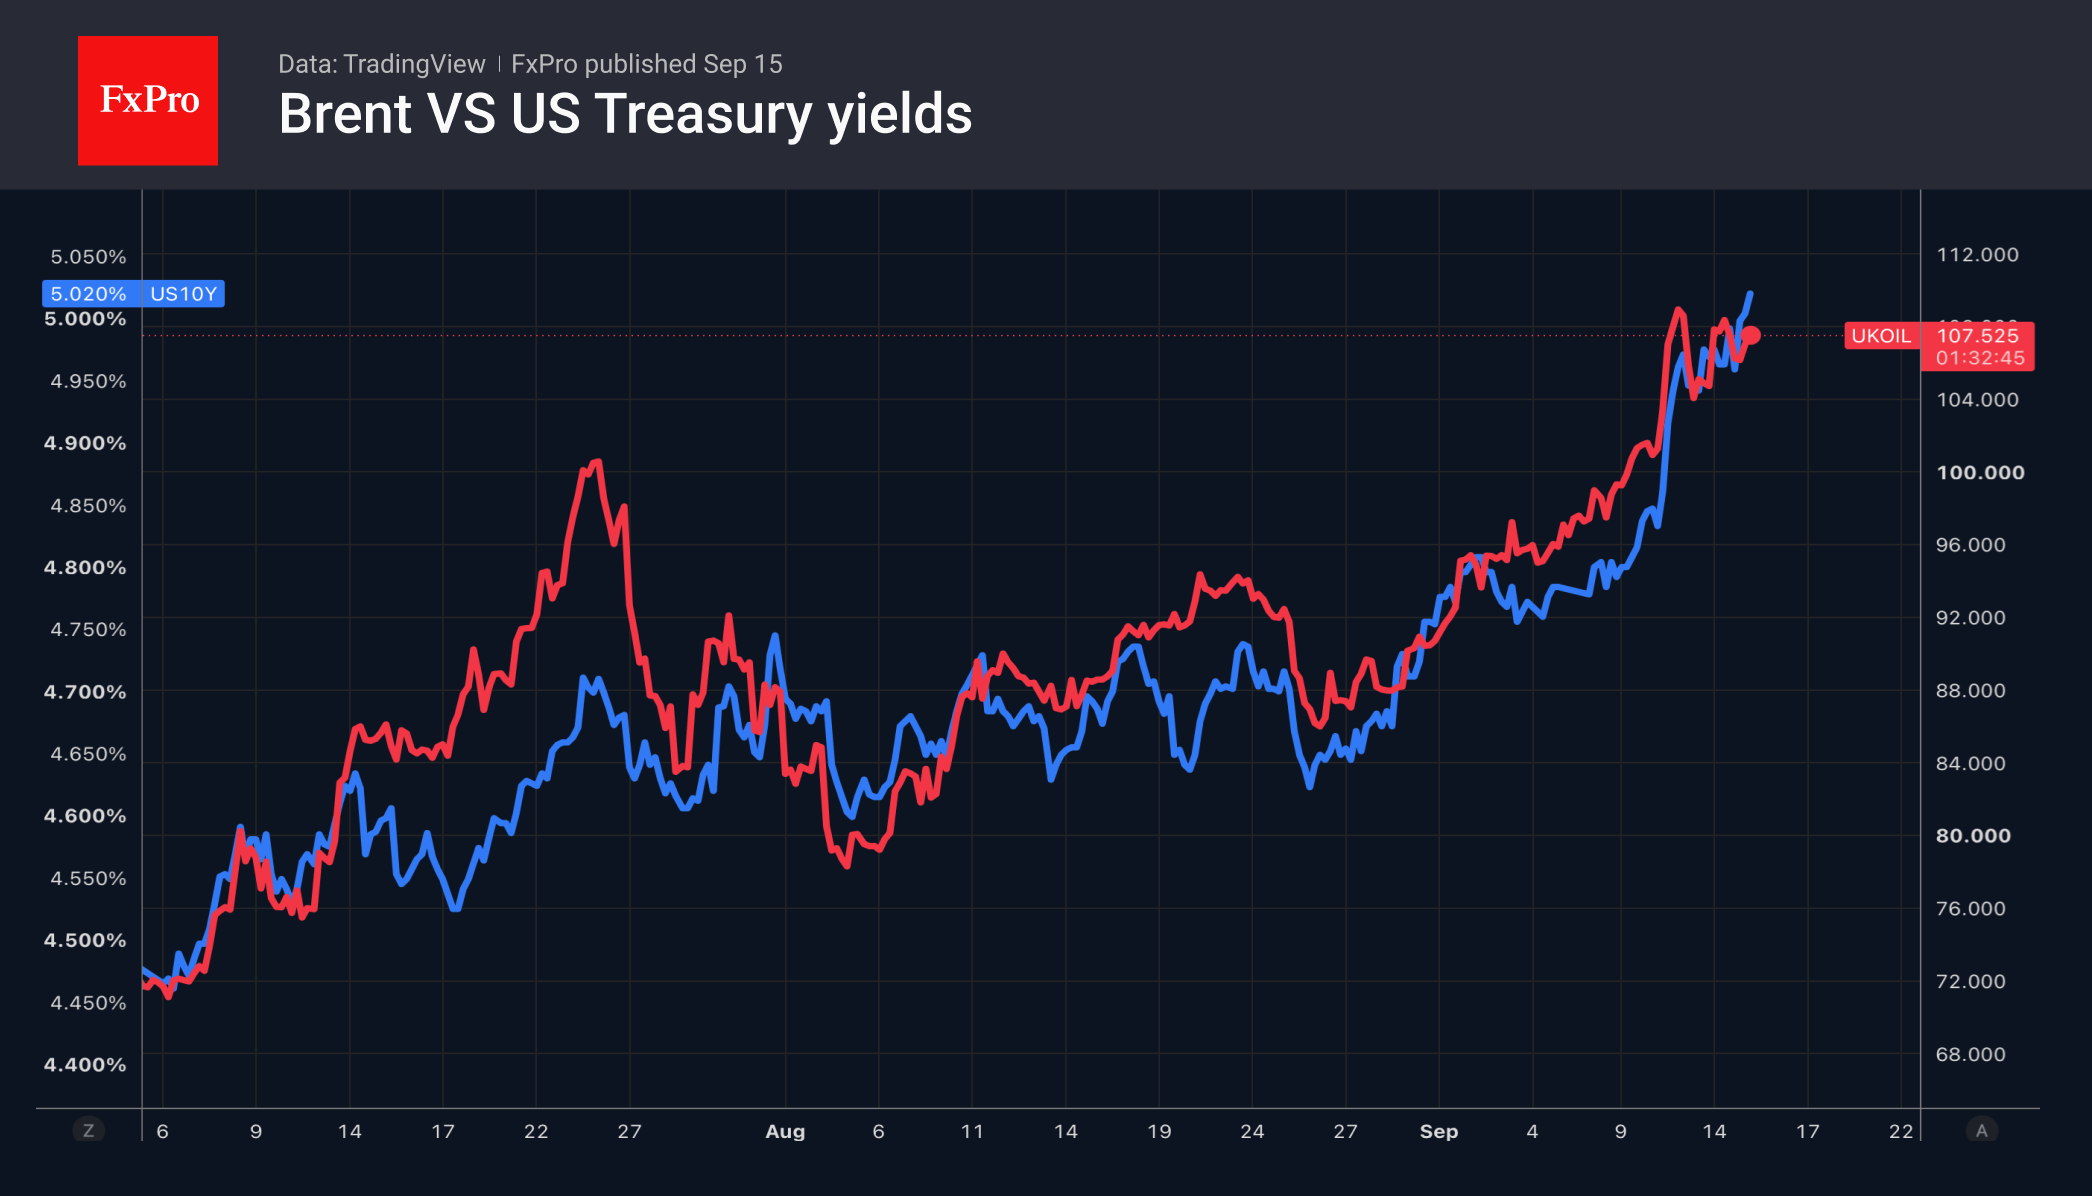
The rise in Brent prices, driven by supply disruption risks from Saudi Arabia, is pushing up Treasury yields and the dollar, thereby fuelling inflationary expectations.
September 14, 2026
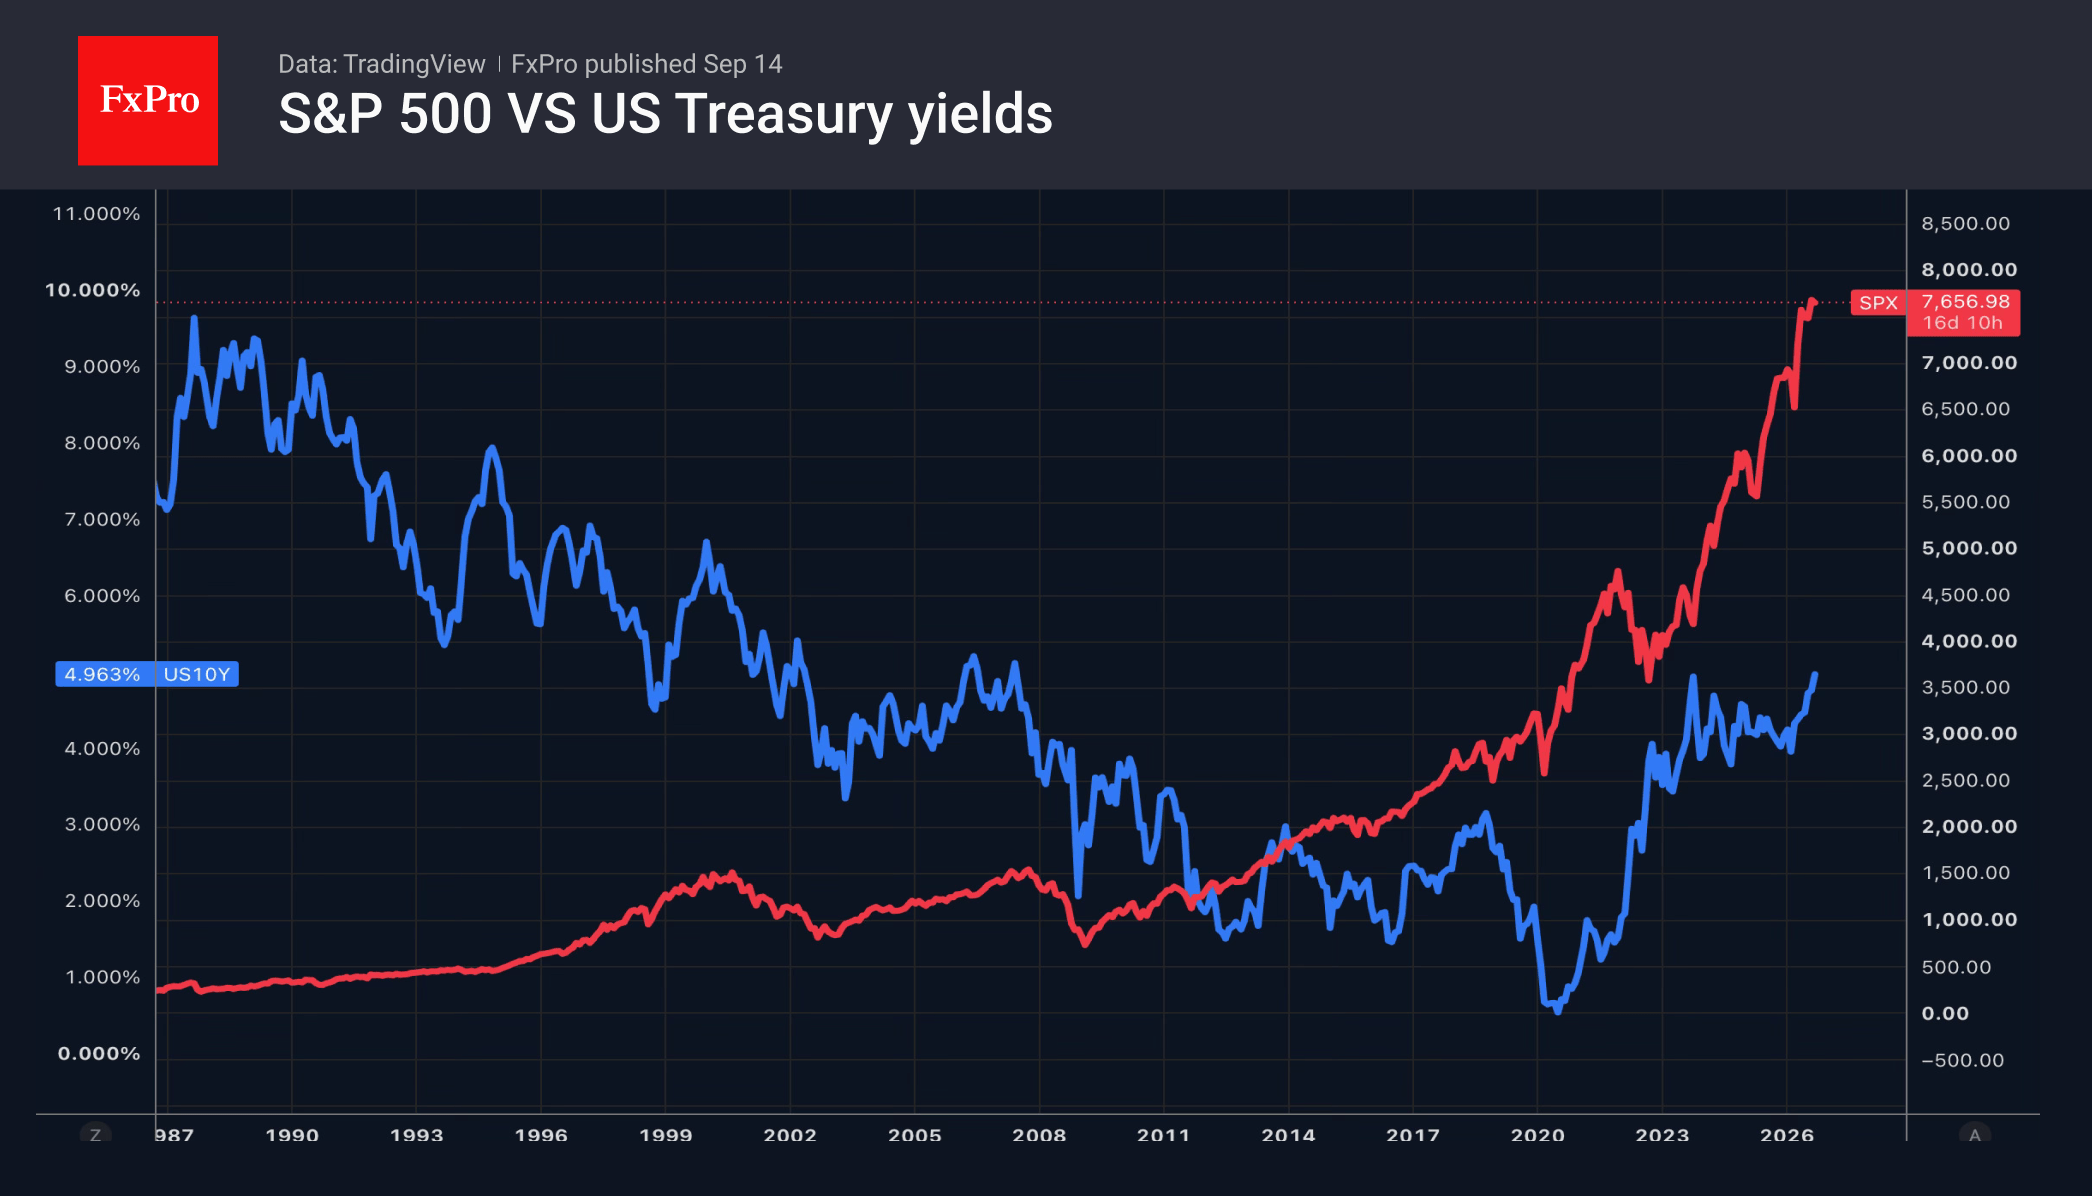
The S&P 500 is rising despite risks from Fed tightening, as markets price in rate hikes, while ETF outflows point to cooling demand.