


Market Overview - Page 2
October 22, 2026
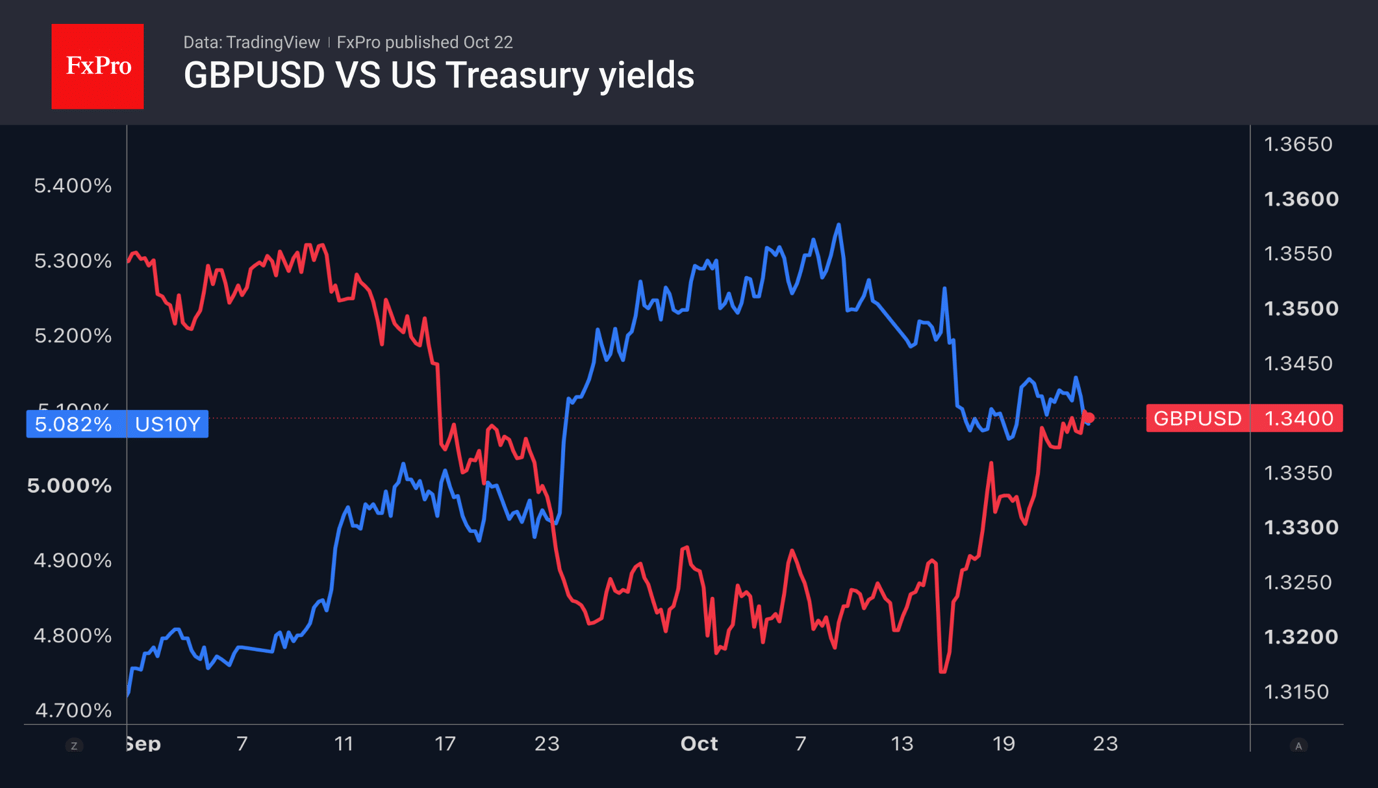
The pound is rising as the dollar slips: political stability, a strong labour market, and faster inflation raise the odds of a BoE hike in November, with markets pricing in 110 bp over the next year.
October 21, 2026
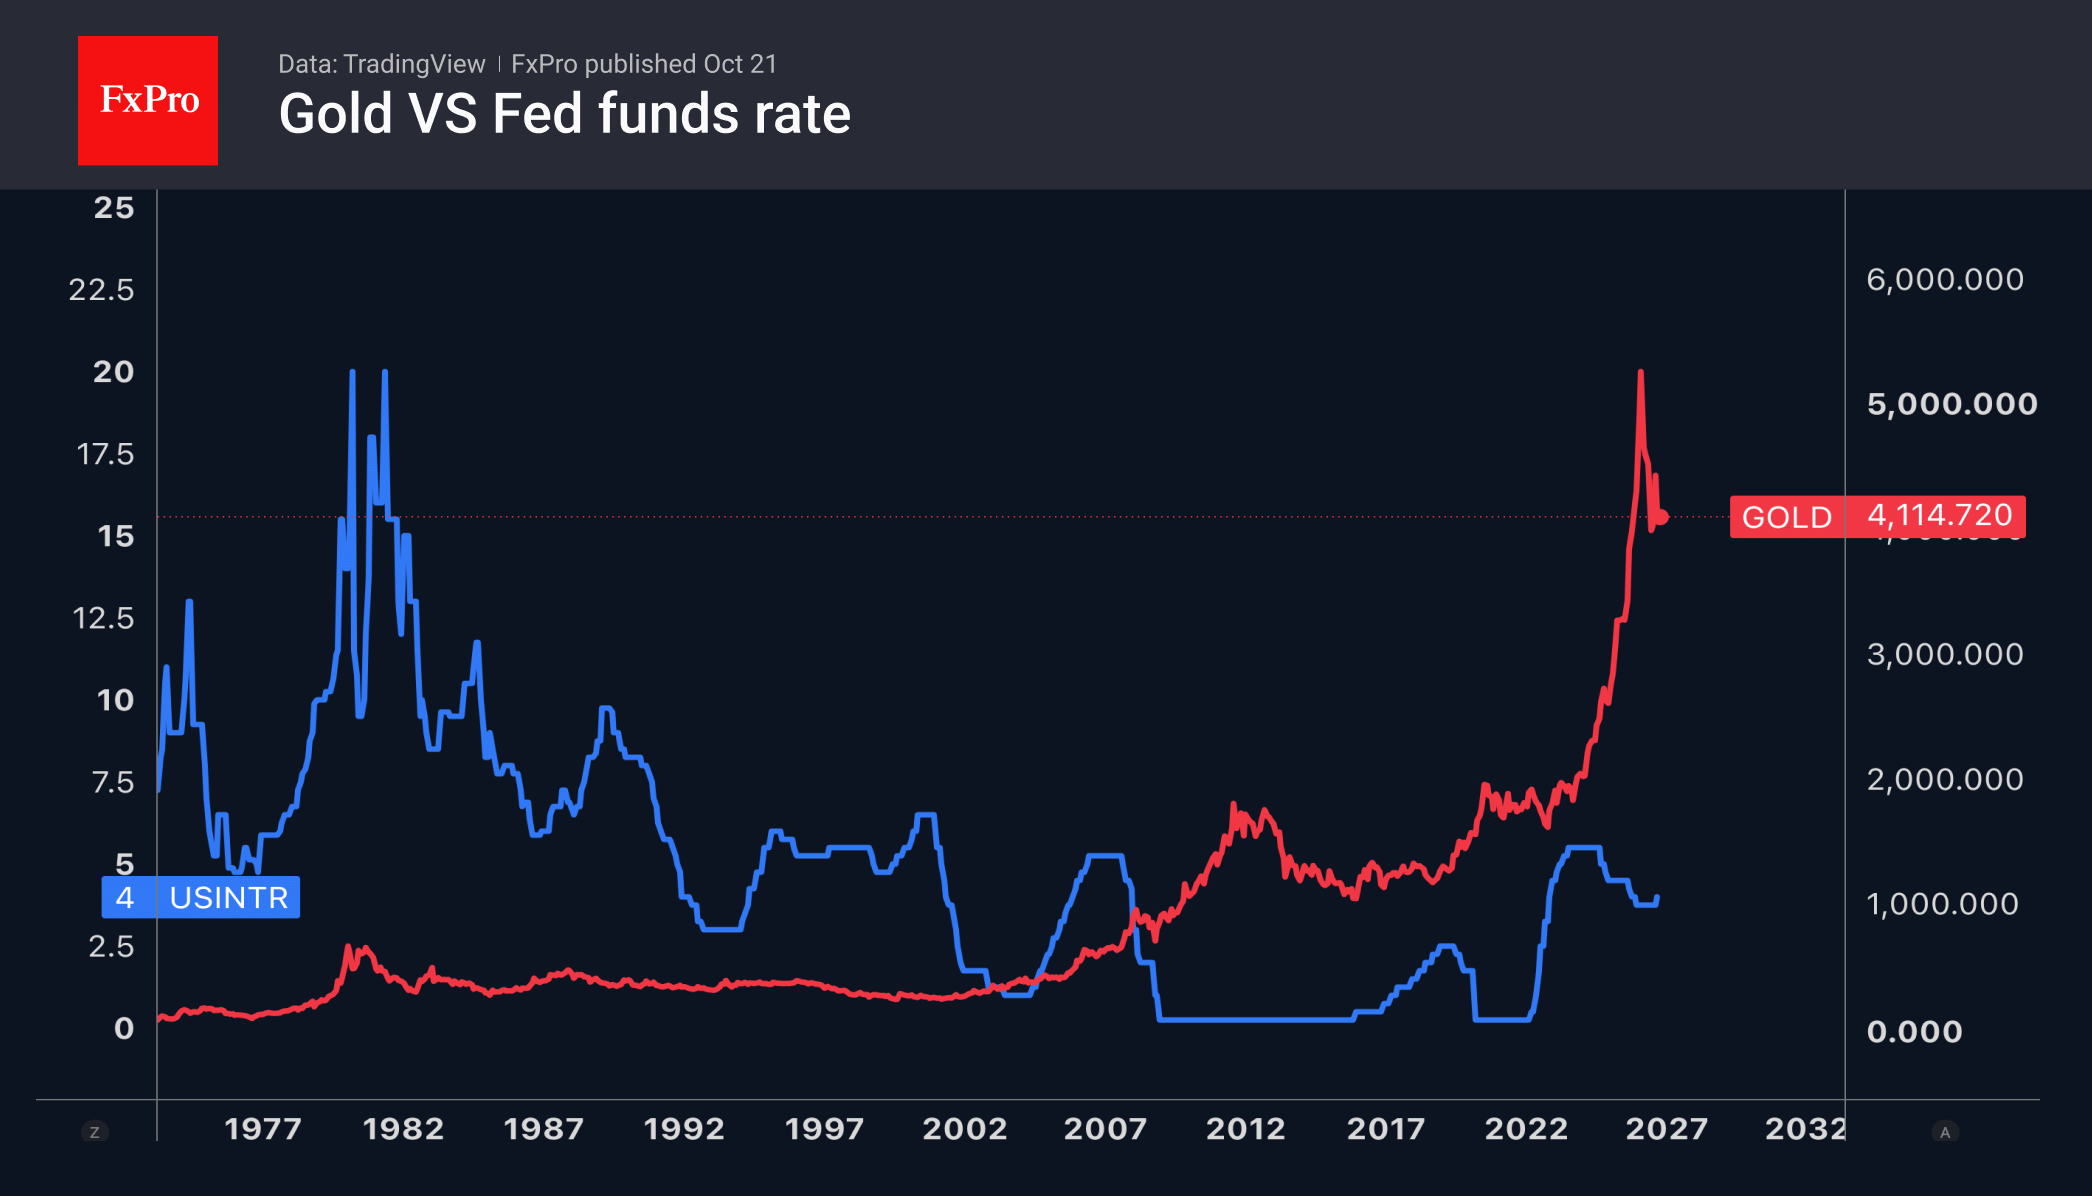
Gold is on track to close lower for the fourth day in a row, despite a weakening US dollar and falling Treasury yields. At first glance, this combination creates a tailwind for precious metals; however, markets rise or fall on.
October 21, 2026
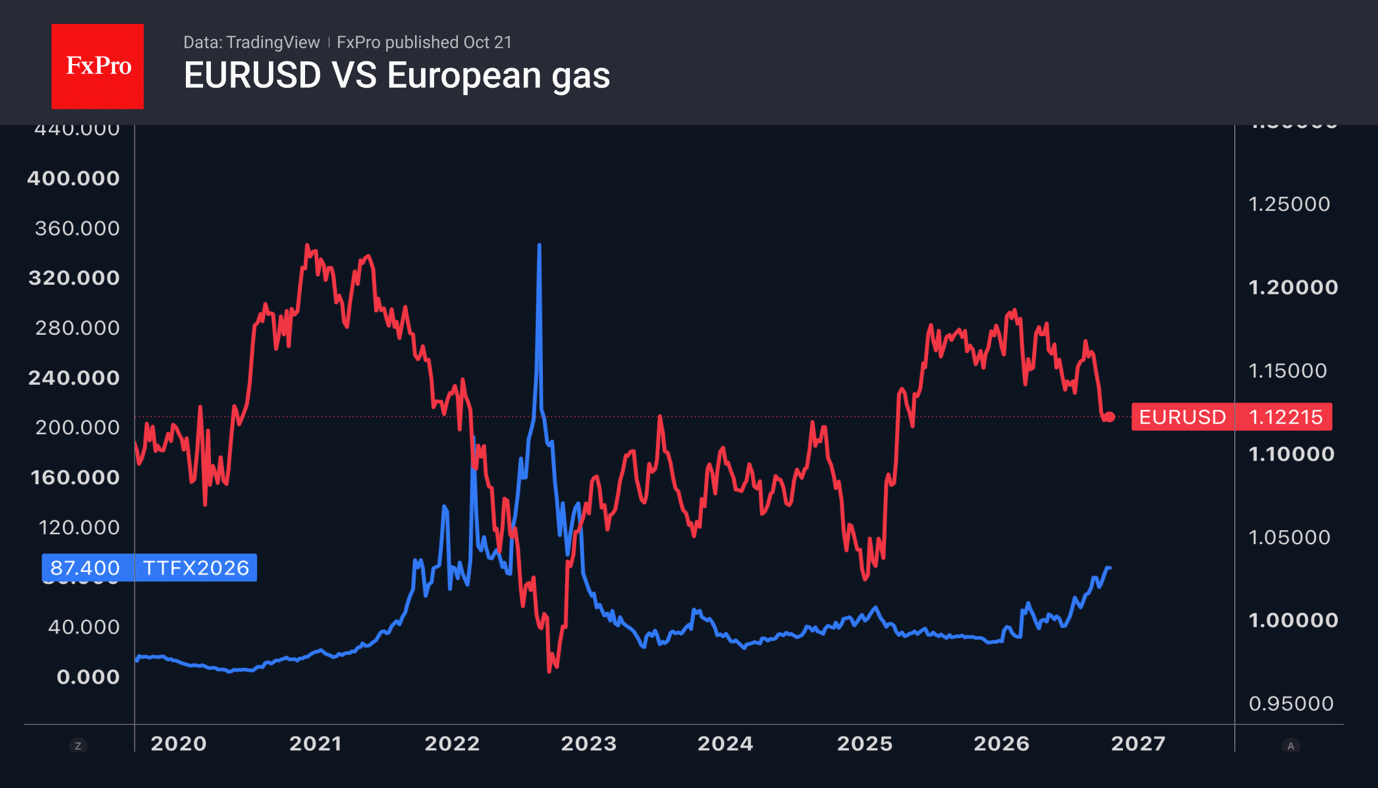
EURUSD may rebound if the risks of a new European debt crisis are exaggerated, the Fed pauses until December, and the dollar gets no help from oil, yields or equities.
October 20, 2026
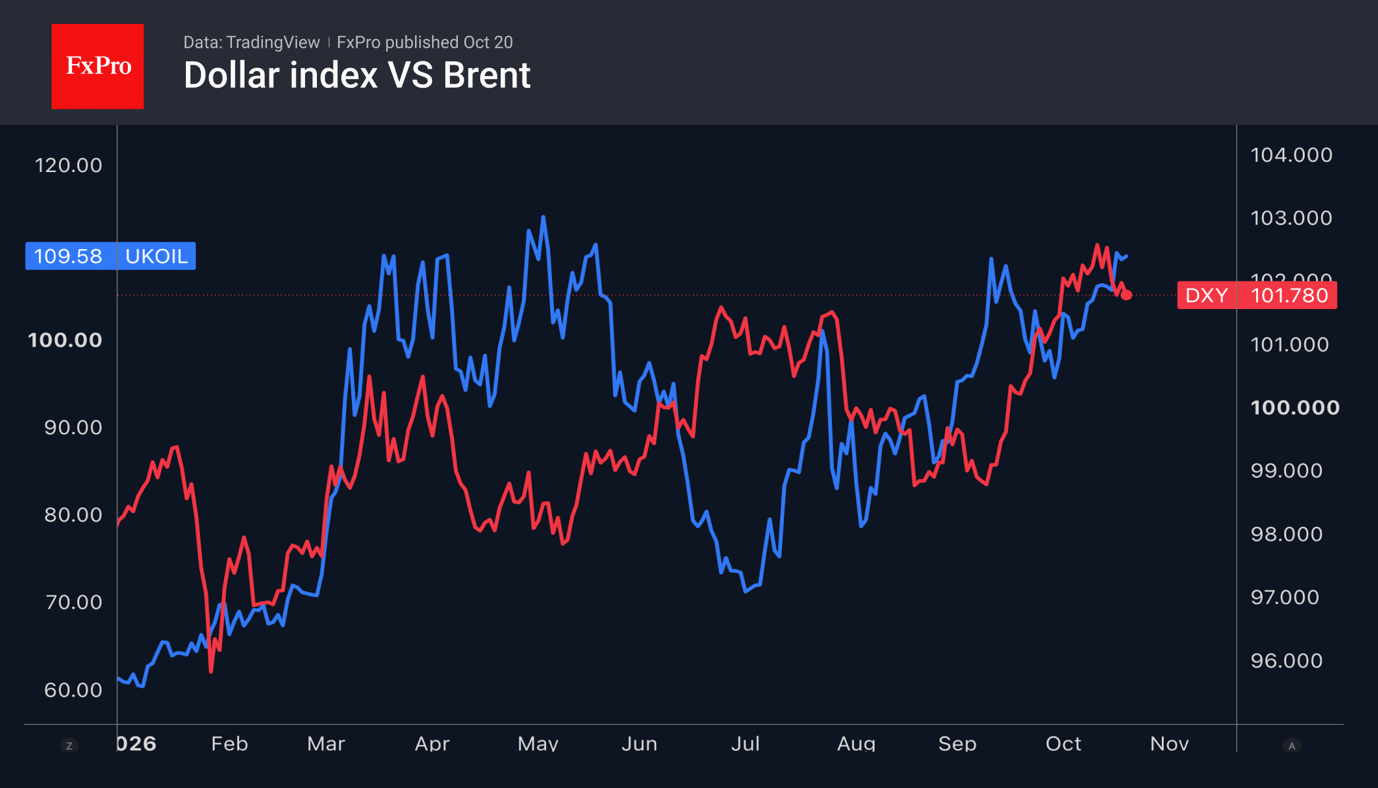
The dollar is falling for a fourth day despite Brent near $110, as markets focus on tech earnings and falling Treasury yields rather than Middle East risks.
October 19, 2026
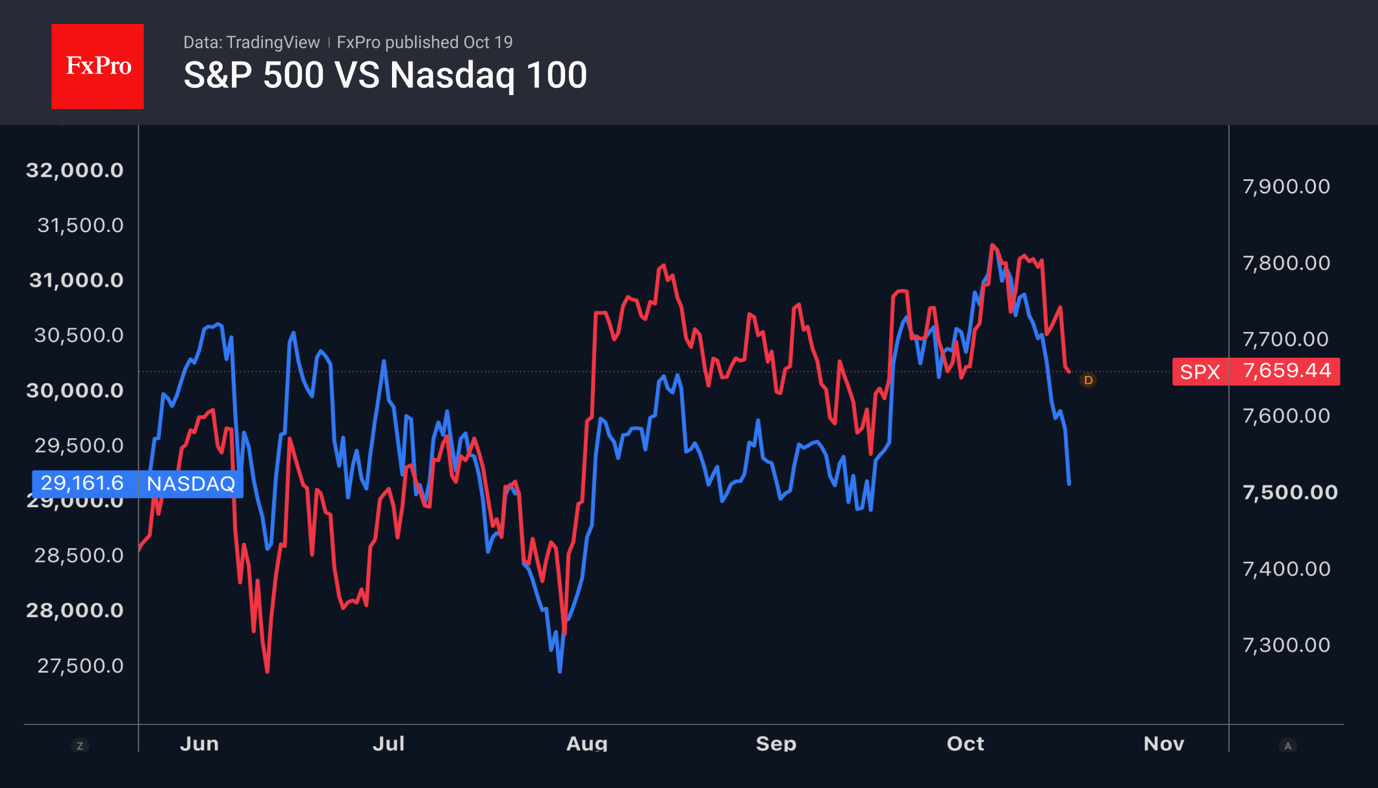
Rising US inflation and inflated AI earnings expectations raise bubble risks for the S&P 500, though solid Q3 results and lower Treasury yields could support the index.
October 19, 2026
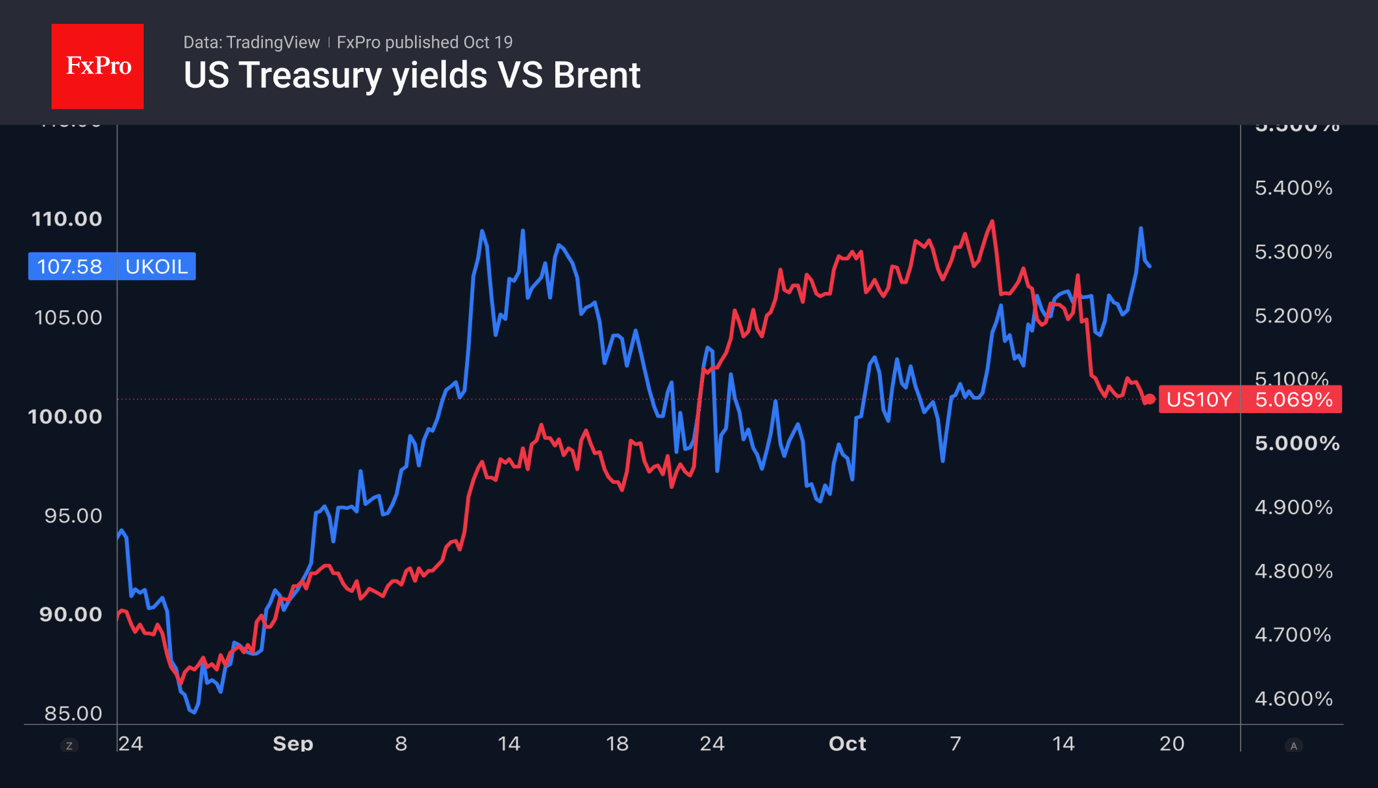
GBPUSD hit a four-week high as the dollar weakened on doubts over AI investment and soft Fed rhetoric, while markets price a 93% chance of a BoE rate hike in November.
October 16, 2026
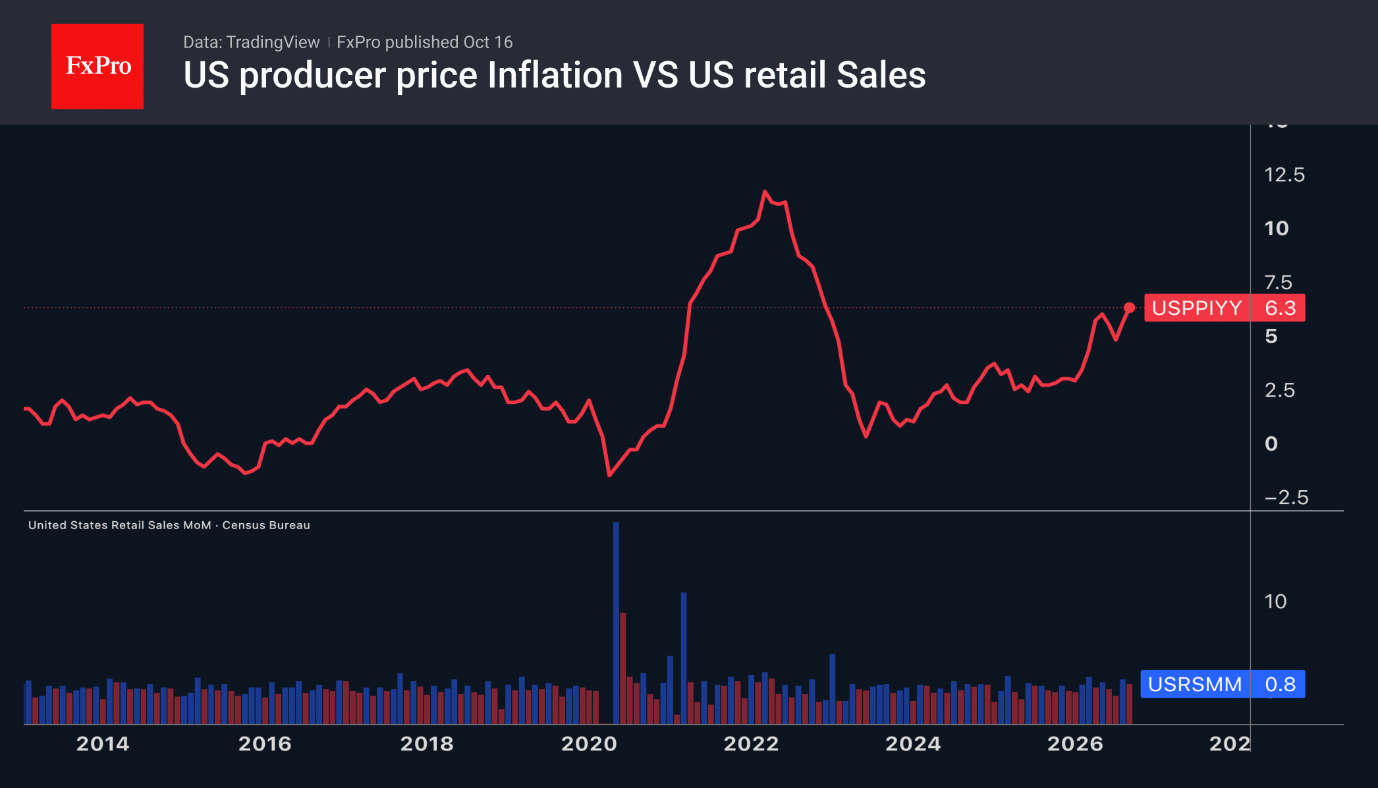
The dollar is weakening in line with Treasury bond yields, whilst the Australian dollar has come under pressure due to a deterioration in the labour market and reduced expectations of an RBA rate rise.
October 15, 2026
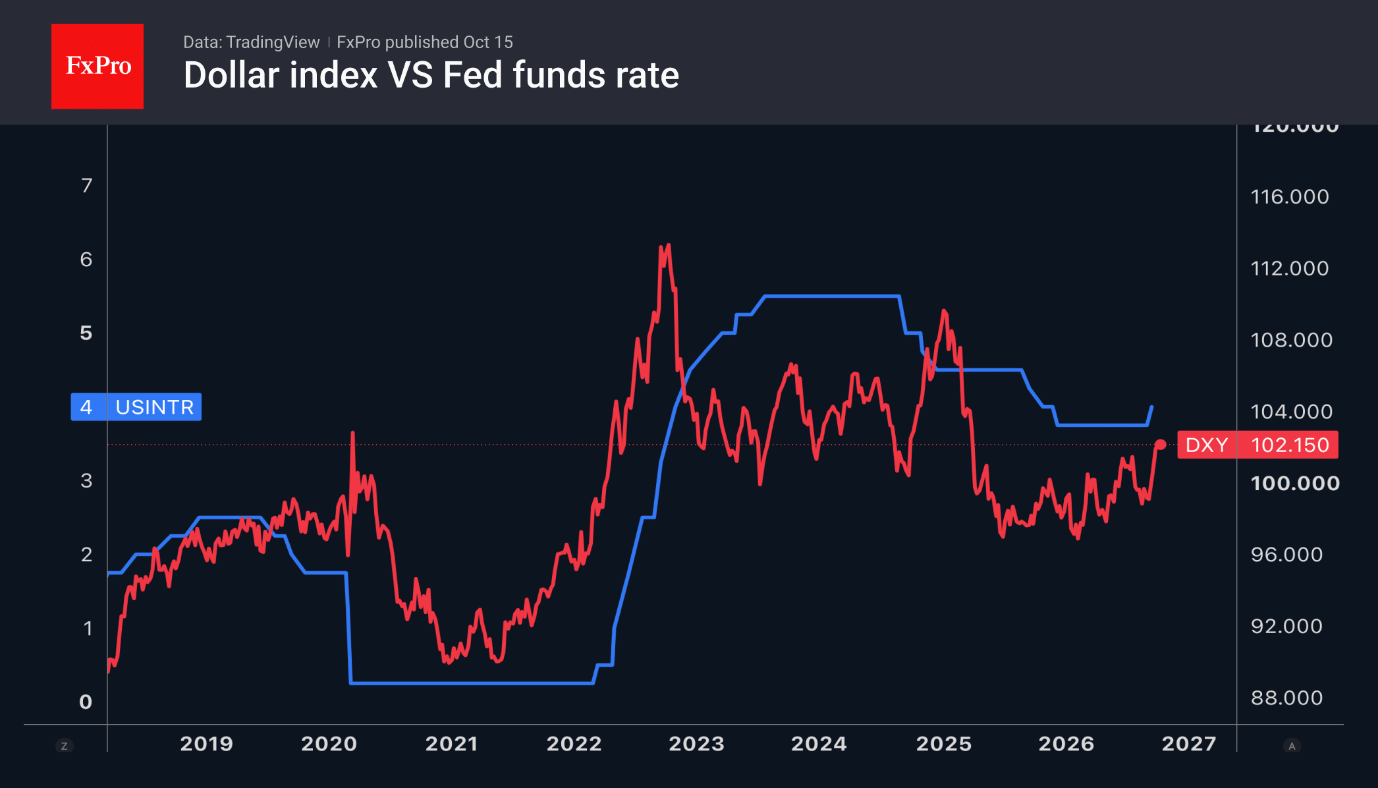
The yen gained on US dollar selling, verbal intervention and hawkish BoJ rhetoric. However, the wide yield spread still supports the USDJPY uptrend.
October 14, 2026
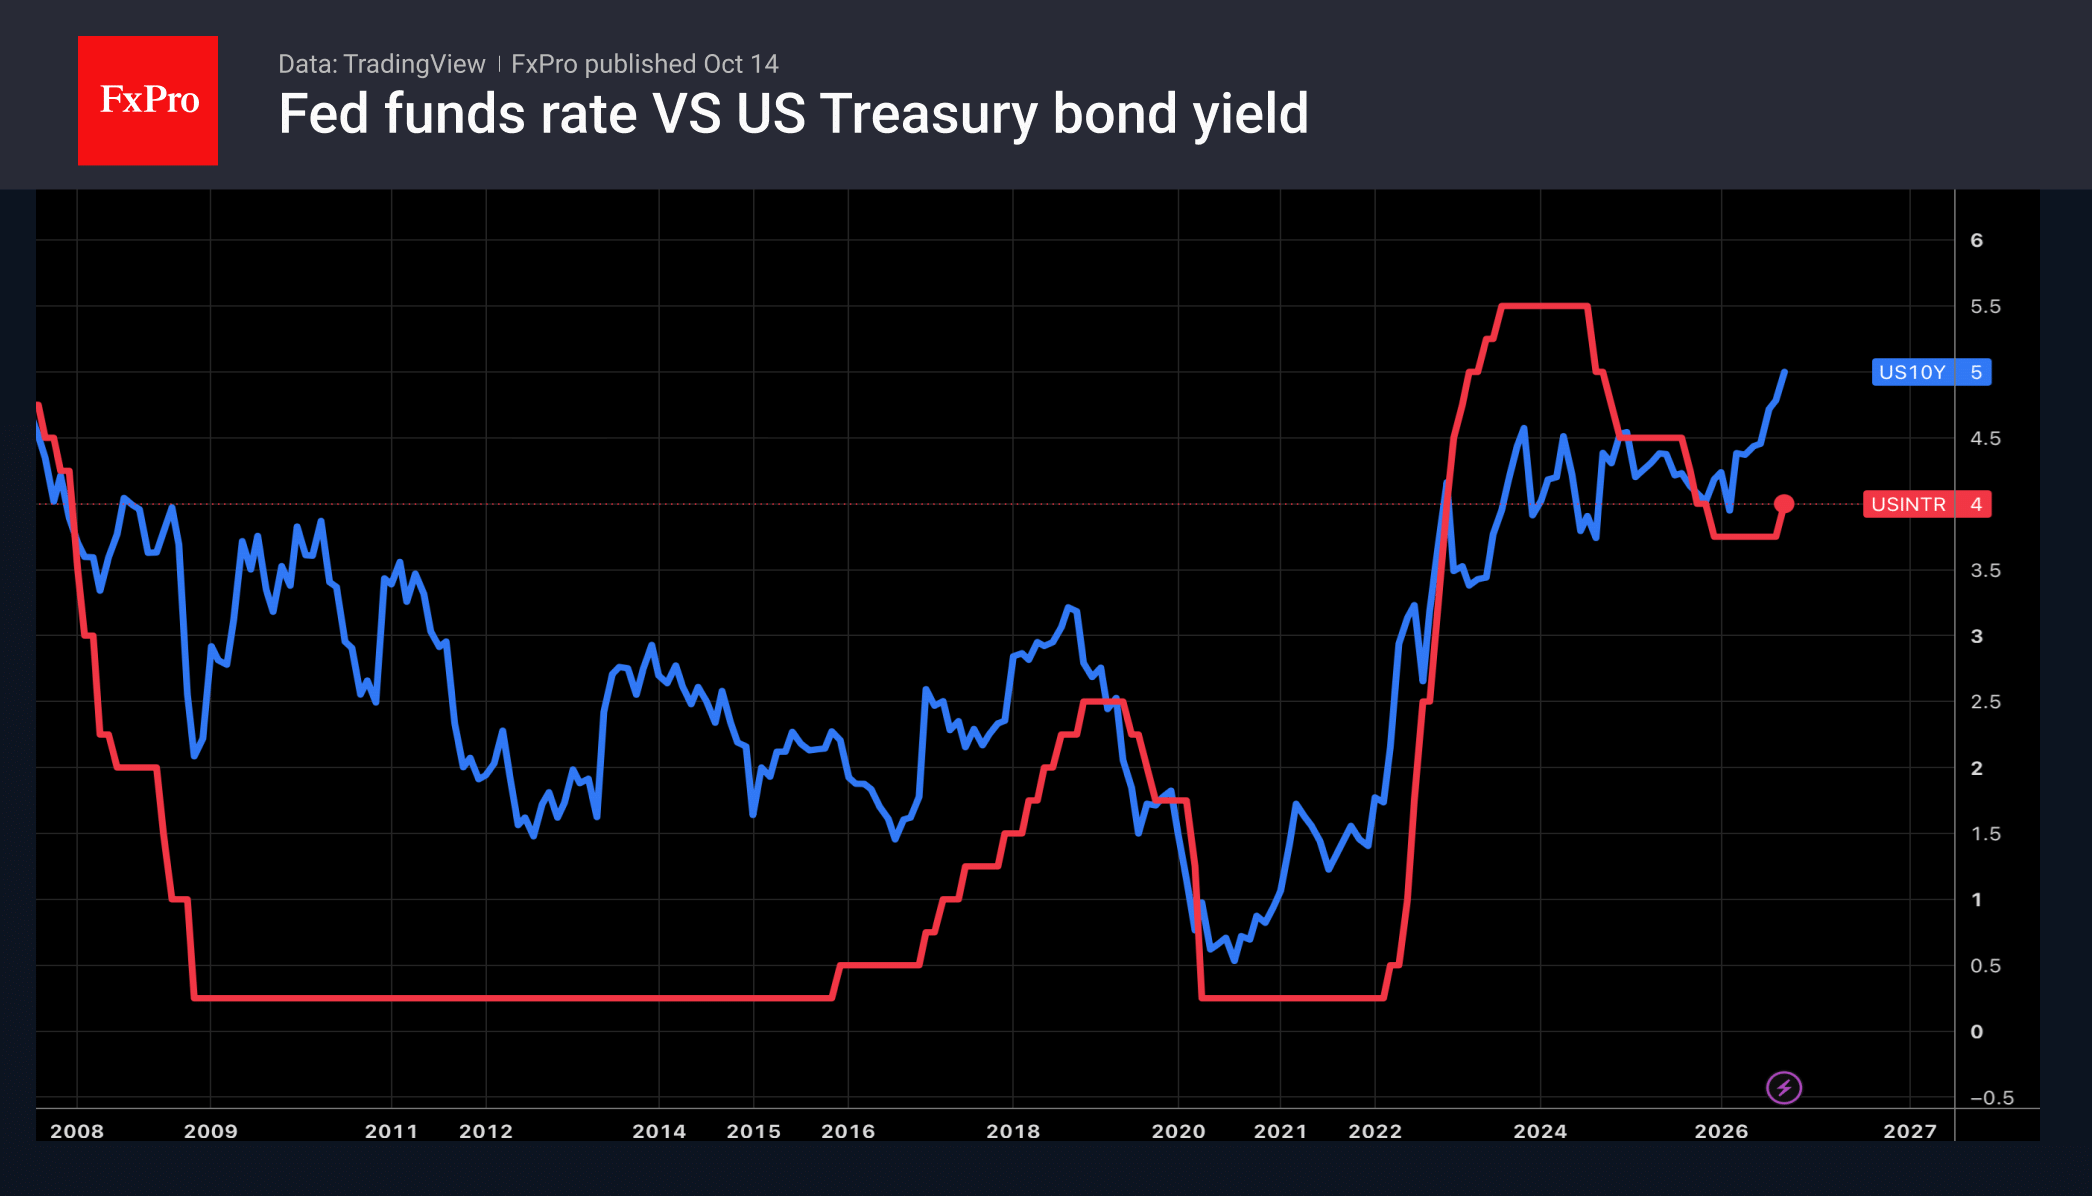
Falling Treasury yields are weighing on the dollar as the Fed resists further hikes. US CPI and equity-market moves will determine the USD’s next direction.
October 13, 2026
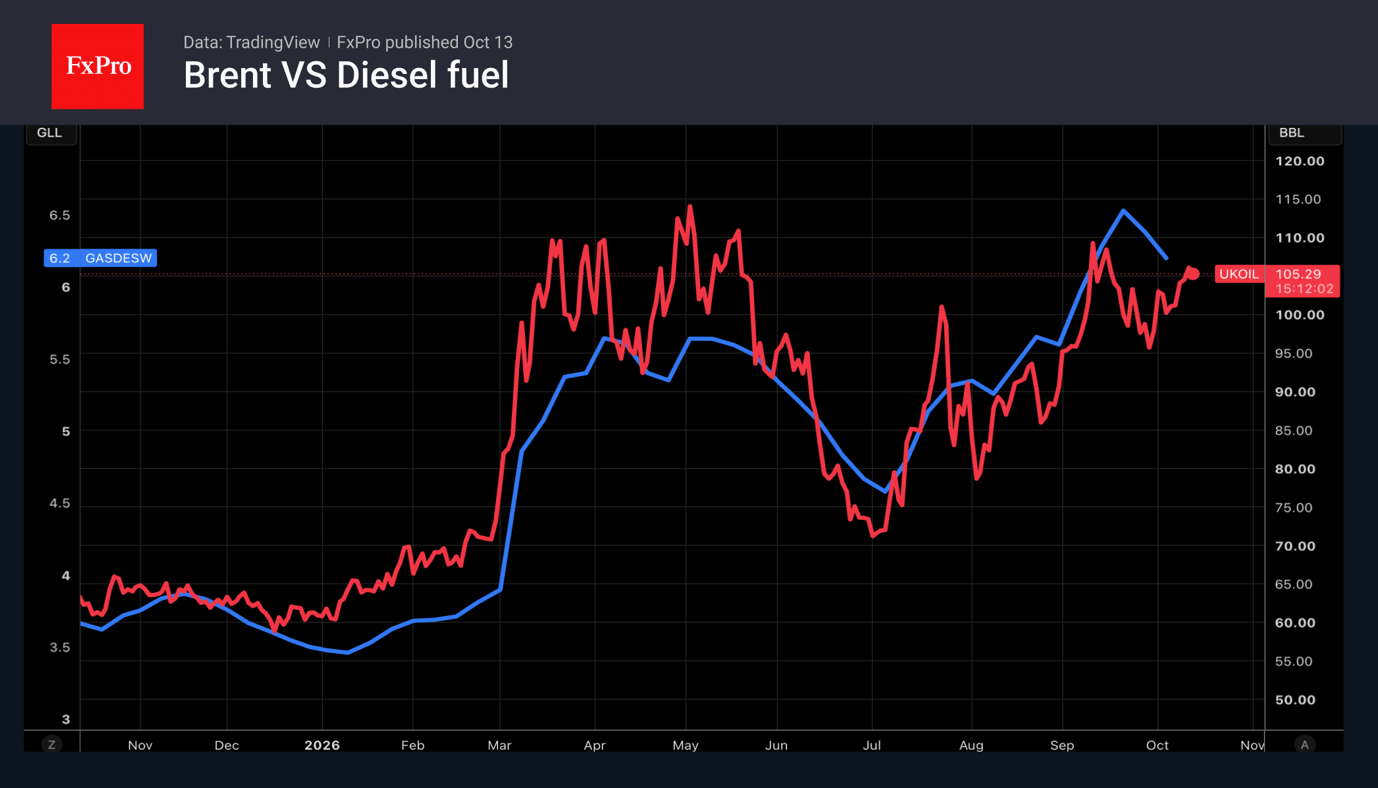
Reduced supplies from the Middle East and rising Chinese imports are supporting the Brent rally, exacerbating inflationary risks, pushing up bond yields and strengthening the dollar.
October 12, 2026
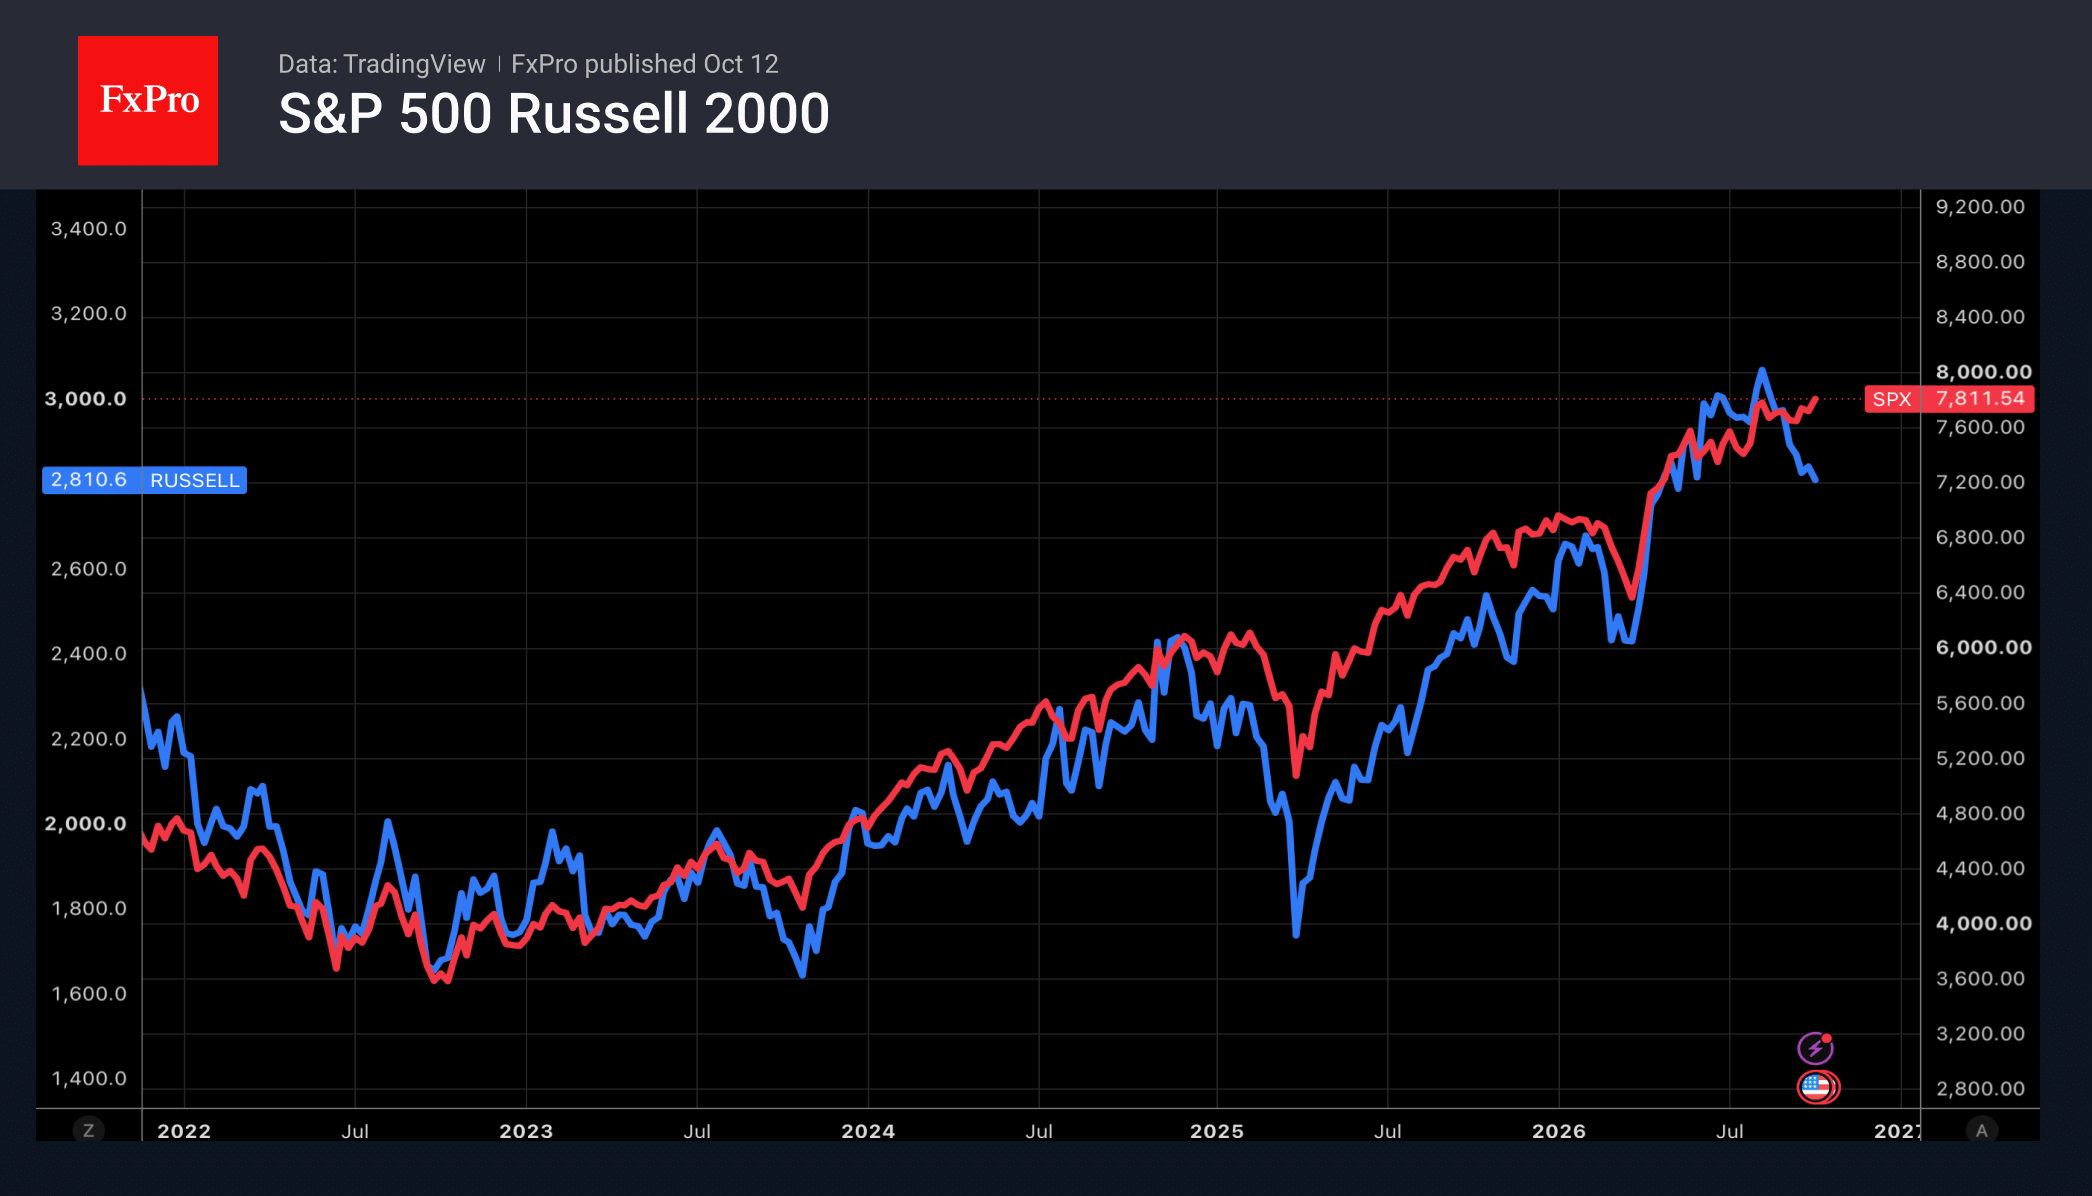
The S&P 500 rally is being supported by a strong economy and the AI boom, but its narrow scope, the weakness of the Russell 2000 and the risk of further Fed rate rises are heightening the threat of a correction.
October 12, 2026
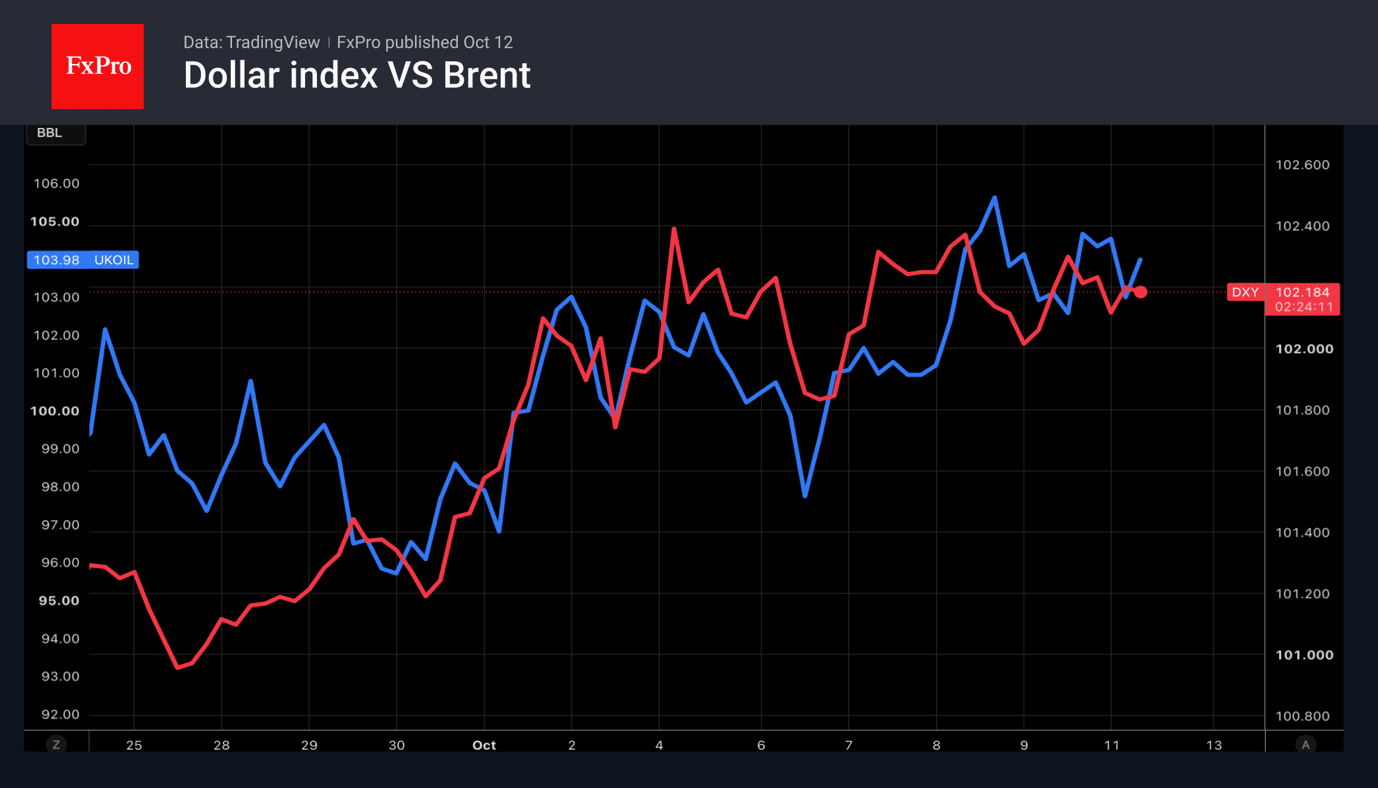
The dollar is supported by elevated Treasury yields and weakness in the euro amid the crisis in France. US inflation may shape expectations for the Fed’s next rate increase.