- High inflation is prolonging the dollar’s rally.
- Treasury yields are rising on the back of hawkish rhetoric from the Fed.
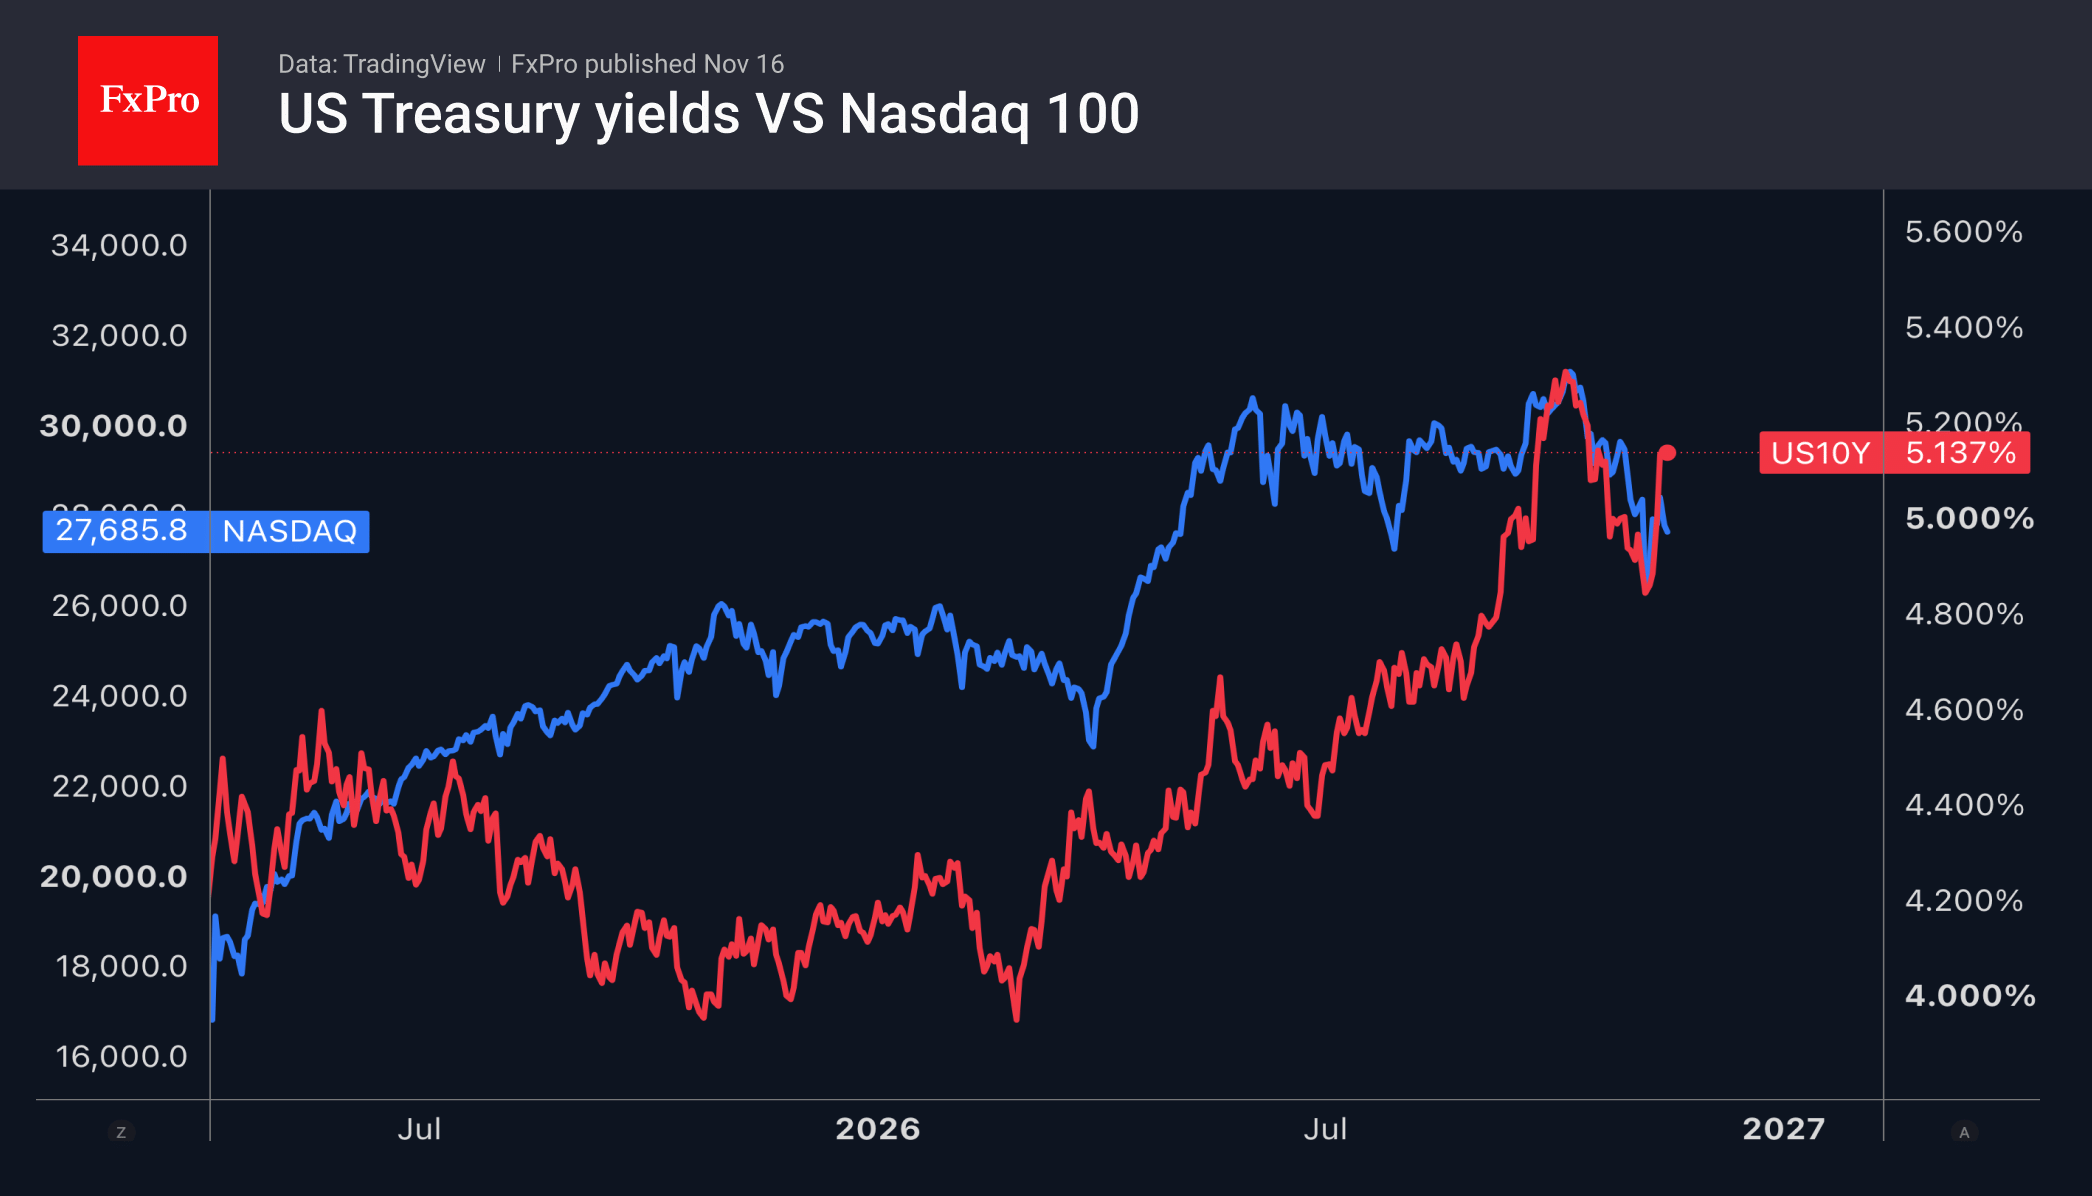
The US dollar posted its best weekly performance since May, driven by several positive factors. The market continued to react to stronger-than-expected US labour market and inflation data, compounded by hawkish rhetoric from FOMC officials. As a result, 10-year Treasury yields returned to levels above 5.10%, paving the way for the USD index to rally to 19-month highs. At the same time, fears about the fate of AI companies have eased somewhat, as signs suggest the fall in NVIDIA’s share price has not triggered a domino effect across the sector, while Reuters reports that applications for Anthropic’s IPO have been oversubscribed many times over.

Source: TradingView, as of 16 November 2026.
The fate of the US dollar and the AI industry is inextricably linked. Investment in new technologies and increased consumption driven by the wealth effect, resulting from the rise in the market value of technology company shares, make a huge contribution to GDP growth. The Atlanta Fed’s GDPNow model points to 3.5% growth in the US economy in the fourth quarter.
Unsurprisingly, the Nasdaq-100‘s fall to its lowest levels since April led to a decline in Treasury yields amid increased AI risk hedging and weakened the dollar. As soon as fears regarding artificial intelligence technologies subsided and inflation data showed an acceleration, EURUSD moved firmly lower.
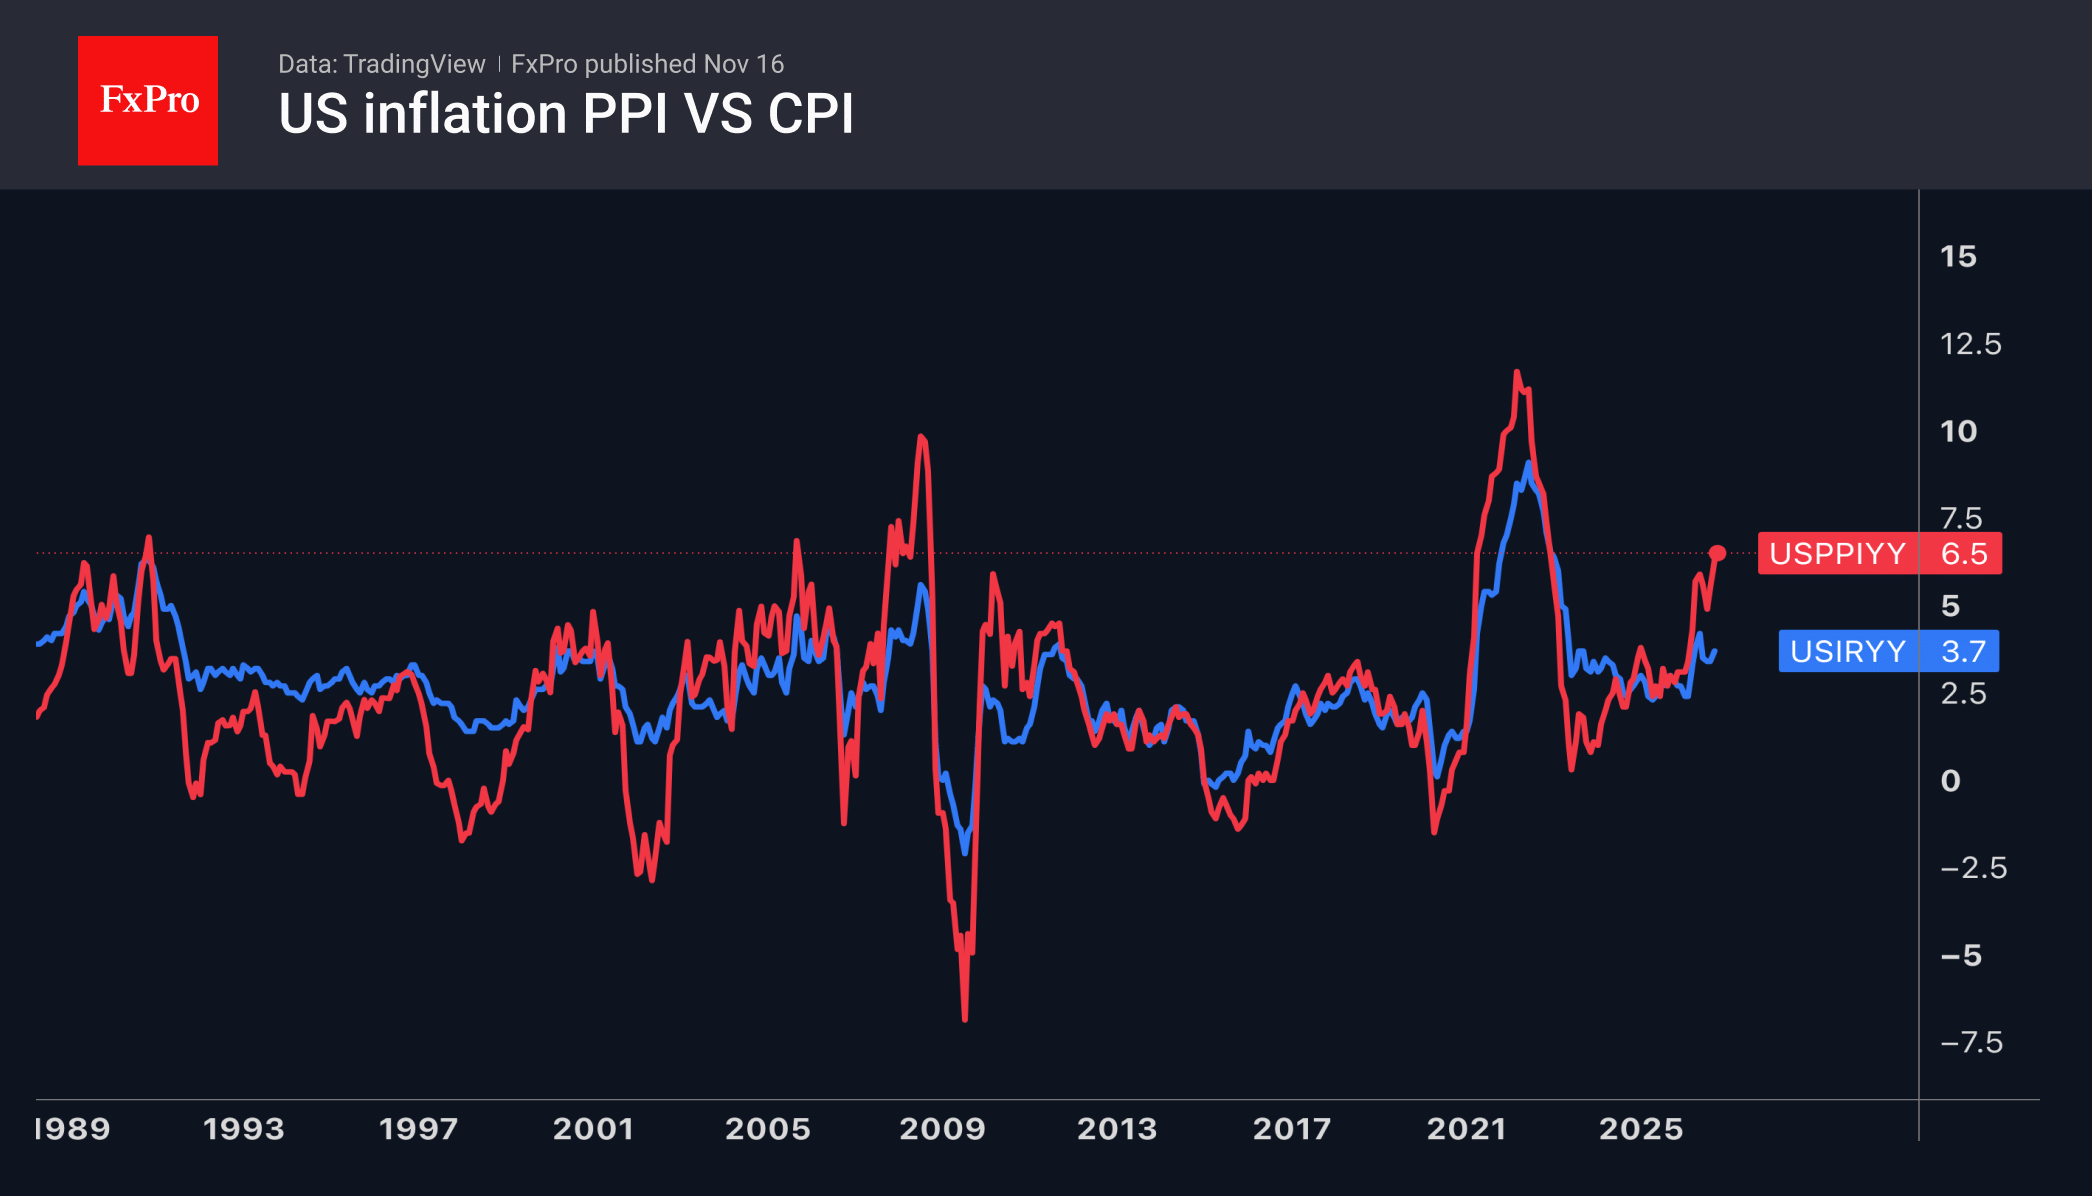
US producer price figures served as the catalyst for the decline in the major currency pair at the end of the week. Year on year, the indicator surged to 6.5%, its highest level since 2022. Against this backdrop, an 80% probability, according to CME FedWatch, of a cumulative 75-basis-point rate hike over the next 12 months seems logical and leaves room for even more decisive tightening, which is what speculators are banking on.
Source: TradingView, as of 16 November 2026.
Meanwhile, USDJPY is fighting a desperate battle to hold the psychologically important 160 level. The bulls are being supported by the wide spread between the Fed and BoJ interest rates, high global risk appetite and the associated demand for carry trades, and the deterioration in Japan’s terms of trade due to high energy prices. Morgan Stanley forecasts the US dollar will rise to ¥162 by the fourth quarter of 2027.
Goldman Sachs, by contrast, believes that the yen is undervalued by 30% and that next year will see the start of a recovery towards its fair value. As a result, it expects USDJPY to fall to 158, 155 and 150 over 3, 6 and 12 months.
Japan’s first GDP decline since July–September 2025, an annualised 0.1% q/q contraction in the third quarter, did not trigger any significant reaction in the yen.
What to watch
Base case: in our view, as long as US inflation keeps accelerating and Treasury yields hold above 5%, the dollar remains supported.
Risk: a return of AI fears and a fall in the Nasdaq-100 could push yields lower again and weaken the dollar; for USDJPY, the risk is Japanese intervention above 160.
Upcoming: US retail sales on Tuesday, 17 November; the FOMC minutes, UK inflation and a speech by the Bank of England Governor on Wednesday, 18 November; Australian employment data on Thursday, 19 November. Check the economic calendar for more events.
The FxPro Analyst Team